


Published by The Morton Group with AtCoastal Realty | Todd Morton, REALTOR and Owner | October 23, 2026
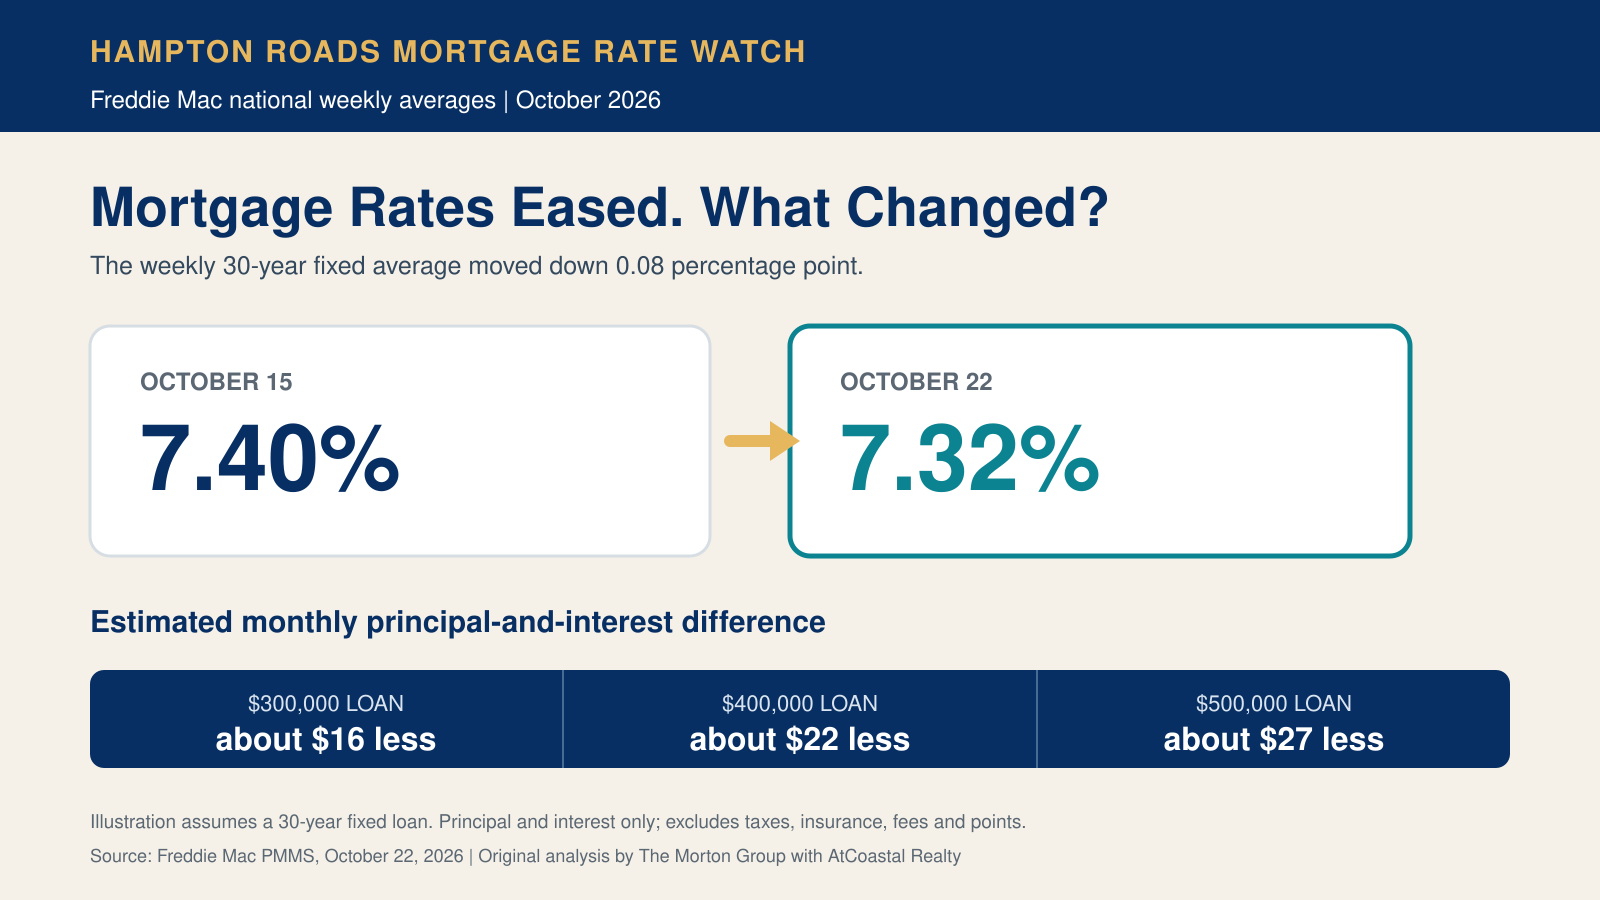
The short answer: Freddie Mac's national average 30-year fixed mortgage rate fell from 7.40% on October 15 to 7.32% on October 22, 2026. For a $400,000, 30-year loan, that 0.08 percentage-point change reduces estimated monthly principal and interest by about $21.80.
That is useful movement, but it is not a reason to rush into or out of a Hampton Roads purchase. The bigger opportunity may come from comparing lender offers, understanding points and credits, and negotiating the right property at a payment that fits your budget.
How much does a move from 7.40% to 7.32% change the payment?
The examples below apply the same two rates to three hypothetical 30-year fixed loans. They are calculations, not lender quotes.
| Loan amount | Payment at 7.40% | Payment at 7.32% | Monthly difference |
|---|---|---|---|
| $300,000 | $2,077.14 | $2,060.79 | $16.35 |
| $400,000 | $2,769.52 | $2,747.72 | $21.80 |
| $500,000 | $3,461.90 | $3,434.65 | $27.25 |
Calculation assumptions: 30-year fixed-rate loan with 360 payments and the stated rate held for the full term. Figures include principal and interest only. They exclude property taxes, homeowners insurance, mortgage insurance, association fees, points and closing costs. Totals are rounded to the nearest cent.
Why could your actual Hampton Roads rate be different?
Freddie Mac's weekly figure is a national market benchmark, not a local advertised rate or a commitment from a lender. A borrower's quote can vary based on credit profile, loan program, down payment, property type, occupancy, points, lender credits and the length of the rate lock.
The Consumer Financial Protection Bureau also notes that the interest rate is only one part of a mortgage's cost. When reviewing a Loan Estimate, compare the rate, annual percentage rate, points, lender credits, closing costs and the "In 5 years" comparison using the same loan type and assumptions.
What should Hampton Roads buyers do with this week's rate change?
1. Refresh the complete monthly payment
Ask your lender to rerun principal, interest, estimated taxes, insurance, mortgage insurance and HOA or condo dues for the homes you are actually considering. A small rate change does not erase a tax, insurance or association-cost difference between two properties.
2. Compare Loan Estimates on the same day
Mortgage pricing can move quickly. Request comparable offers for the same loan amount, loan type, down payment and lock period. A lower rate paired with expensive points may not be the best fit if you expect to move or refinance before reaching the break-even point.
3. Confirm whether the rate is locked
The CFPB advises buyers to check the top of page one of the Loan Estimate for the lock status and expiration. Ask what an extension would cost if closing is delayed, and whether the lender offers any option if market pricing improves after locking.
4. Keep the national headline in local context
A lower weekly average may help affordability at the margin, but inventory, neighborhood competition and property condition still shape the offer. Review the latest verified local figures in our Southside Hampton Roads real estate market report before treating a national rate move as proof that local leverage has changed.
The local takeaway
An eight-basis-point weekly decline is welcome, but the payment effect is modest. For many buyers, a better lender comparison, a carefully evaluated seller credit or a different property price will move the monthly budget more than this one weekly change.
The Morton Group can help connect the financing numbers to current homes, neighborhood options and an offer strategy. Contact us to discuss your Hampton Roads home search.
Sources
- Freddie Mac: Primary Mortgage Market Survey, October 22, 2026.
- Consumer Financial Protection Bureau: Compare and negotiate your loan offers, checked October 23, 2026.
- Consumer Financial Protection Bureau: What is a mortgage rate lock?, checked October 23, 2026.