


Published by The Morton Group with AtCoastal Realty | Todd Morton, REALTOR and Owner | October 20, 2026
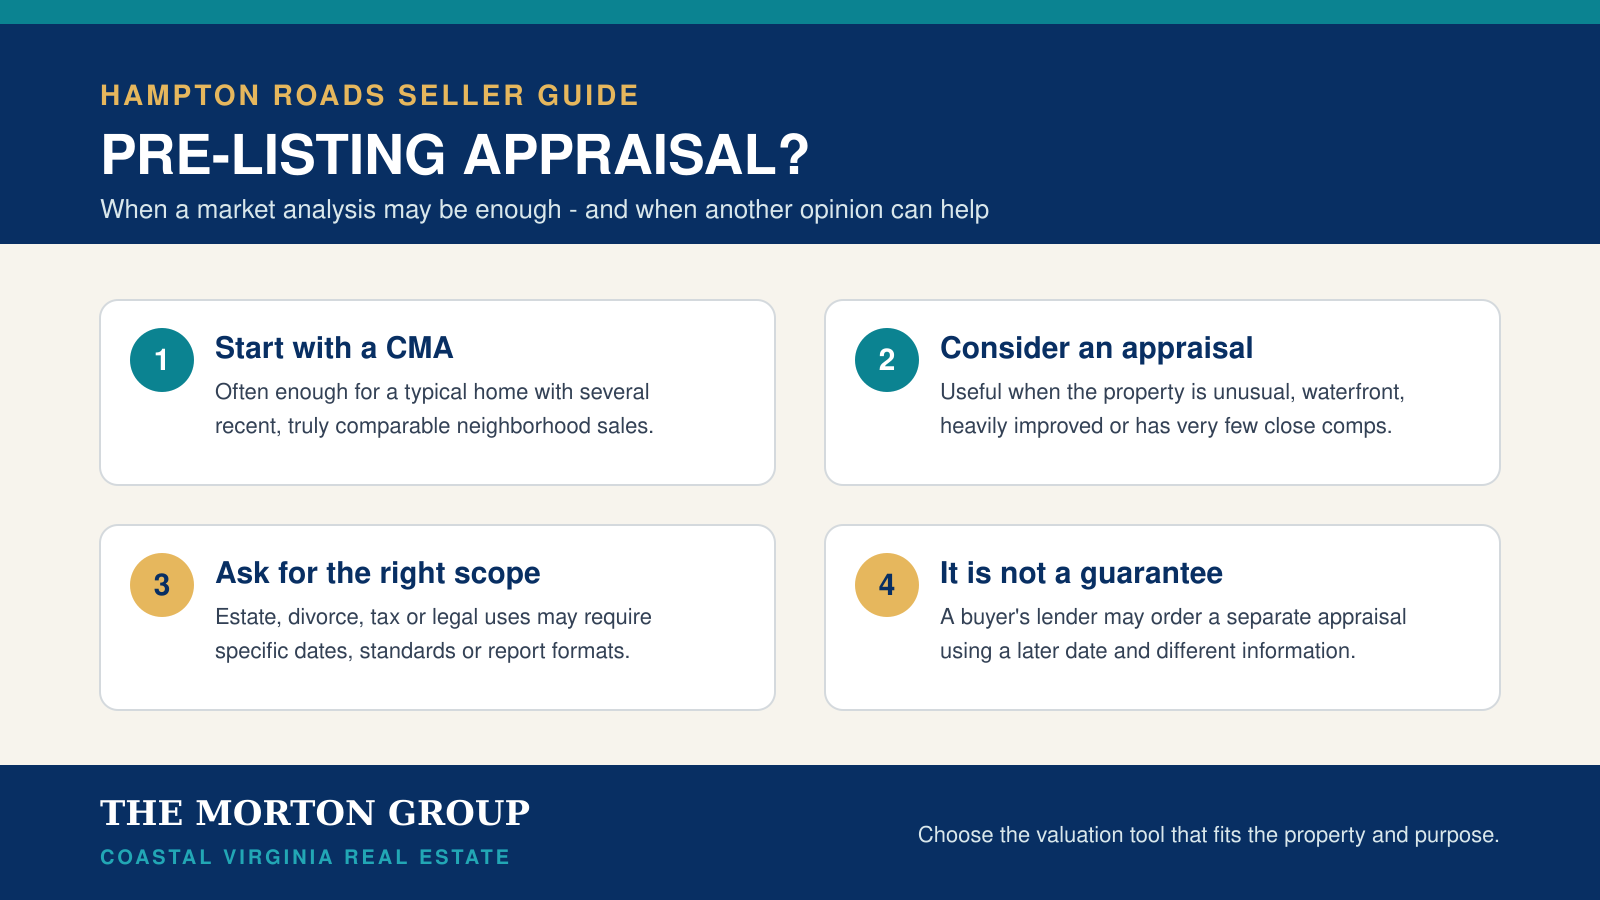
Most Hampton Roads sellers do not need to order a pre-listing appraisal. When a home has several recent, truly comparable sales, a detailed comparative market analysis (CMA) is usually the best first step. A pre-listing appraisal may be useful when the property is unusual, the comparable sales are thin, or an independent opinion of value is needed for an estate, divorce, tax, or legal purpose.
There is one important limit: a seller-paid appraisal does not replace an appraisal later ordered by a buyer's lender, and it does not guarantee that another appraiser will reach the same conclusion.
What is the difference between a CMA and an appraisal?
A CMA is a real estate agent's pricing analysis. It combines recent closed sales with pending and active competition, property condition, buyer expectations, and a recommended listing strategy. It is not an appraisal.
An appraisal is an independent written opinion of market value as of a specified date, prepared by a licensed or certified appraiser. The Consumer Financial Protection Bureau explains that lenders commonly use appraisals to evaluate the property supporting a mortgage. Fannie Mae defines market value as the most probable price in a competitive and open market under normal conditions, without unusual pressure or concessions.
| Seller situation | Practical first step |
|---|---|
| Typical home with several recent, similar neighborhood sales | Start with a detailed CMA |
| Waterfront, acreage, custom construction, or major additions | Consider an appraisal if comparable sales are limited |
| Estate, divorce, tax, or legal matter | Ask the attorney or tax professional what report and effective date are required |
| Ordinary sale involving buyer financing | Expect the buyer's lender to order its own appraisal |
When is a CMA usually enough?
A CMA is generally a strong starting point when the home fits a recognizable neighborhood pattern and recent sales are similar in location, size, age, style, and condition. Fannie Mae's comparable-sales guidance says neighborhood sales are usually the best indicators when suitable examples exist. It also notes that an appraiser may need to use older or more distant sales when true comparables are scarce, with an explanation for those choices.
A pricing recommendation should also account for the homes competing for buyers today. Closed sales show what buyers recently paid; active and pending listings help show the choices buyers are comparing now. For broader local context, review the latest Hampton Roads real estate market report.
When can a pre-listing appraisal help?
An appraisal may add useful independent support when a property's value is difficult to bracket. Hampton Roads examples can include waterfront homes with different water access, large or subdividable lots, custom construction, extensive renovations, converted living areas, detached structures, historic homes, or properties with very few recent comparable sales.
It can also make sense when the intended user needs a formal valuation for a purpose other than marketing. Before ordering one for an estate, tax, divorce, or legal matter, confirm the required report type and effective date with the appropriate attorney, accountant, or other adviser.
Why can the buyer's appraisal still be different?
Value is tied to a specific date and the information available at that time. A later appraiser may inspect a changed condition, select different comparable sales, apply different adjustments, or analyze a market that has moved. The buyer's lender generally selects its own independent appraiser, so a pre-listing report should be treated as preparation, not a promise.
What should a seller ask before ordering an appraisal?
- What is the purpose of the appraisal, and who will rely on it?
- What effective date and report type are appropriate?
- Does the appraiser regularly handle this property type and local area?
- What records would help, such as permits, a survey, floor plans, or an improvement list?
- What are the fee, turnaround time, and inspection requirements?
Virginia sellers can verify an appraiser's credential through the state's official DPOR License Lookup.
The Hampton Roads takeaway
Start with the least complicated tool that can answer the pricing question. For many sellers, that is a well-supported CMA and a candid discussion about condition, competition, and timing. If the home is difficult to compare or a formal independent value is needed, a pre-listing appraisal may be worth considering.
Ask The Morton Group for a property-specific pricing review. We can help you evaluate the comparable sales first and decide whether an appraisal is likely to add value before you spend the money.
This article is general educational information and is not appraisal, legal, or tax advice.
Sources
- Consumer Financial Protection Bureau: What are appraisals? Updated March 12, 2025.
- Fannie Mae Selling Guide: Comparable Sales. Policy effective June 4, 2025; guide page published October 7, 2026.
- Fannie Mae Selling Guide: Definition of Market Value. Policy effective June 4, 2025; guide page published October 7, 2026.
- Virginia DPOR License Lookup. Accessed October 20, 2026.