


Published by The Morton Group with AtCoastal Realty | Todd Morton, REALTOR and Owner | October 17, 2026
The practical answer: A VA-backed mortgage may be assumable, allowing an approved buyer to take over the seller's existing loan terms. But the opportunity is not automatic. The buyer must qualify, the servicer or VA must approve the transaction, the equity gap must be funded, and the seller must address both liability and VA entitlement before closing.
Why are assumable VA loans getting more attention?
Freddie Mac reported a national average 30-year fixed mortgage rate of 7.40% for the week ending October 15, 2026. That is a national survey average, not a quote available to every Hampton Roads borrower. Still, it explains why buyers may notice a listing with an older VA loan carrying a lower rate.
The potential benefit is the existing loan, not a new mortgage for the full purchase price. The Department of Veterans Affairs confirms that VA-backed loans can be assumed, meaning the buyer takes over the seller's loan instead of opening a new loan for that balance.
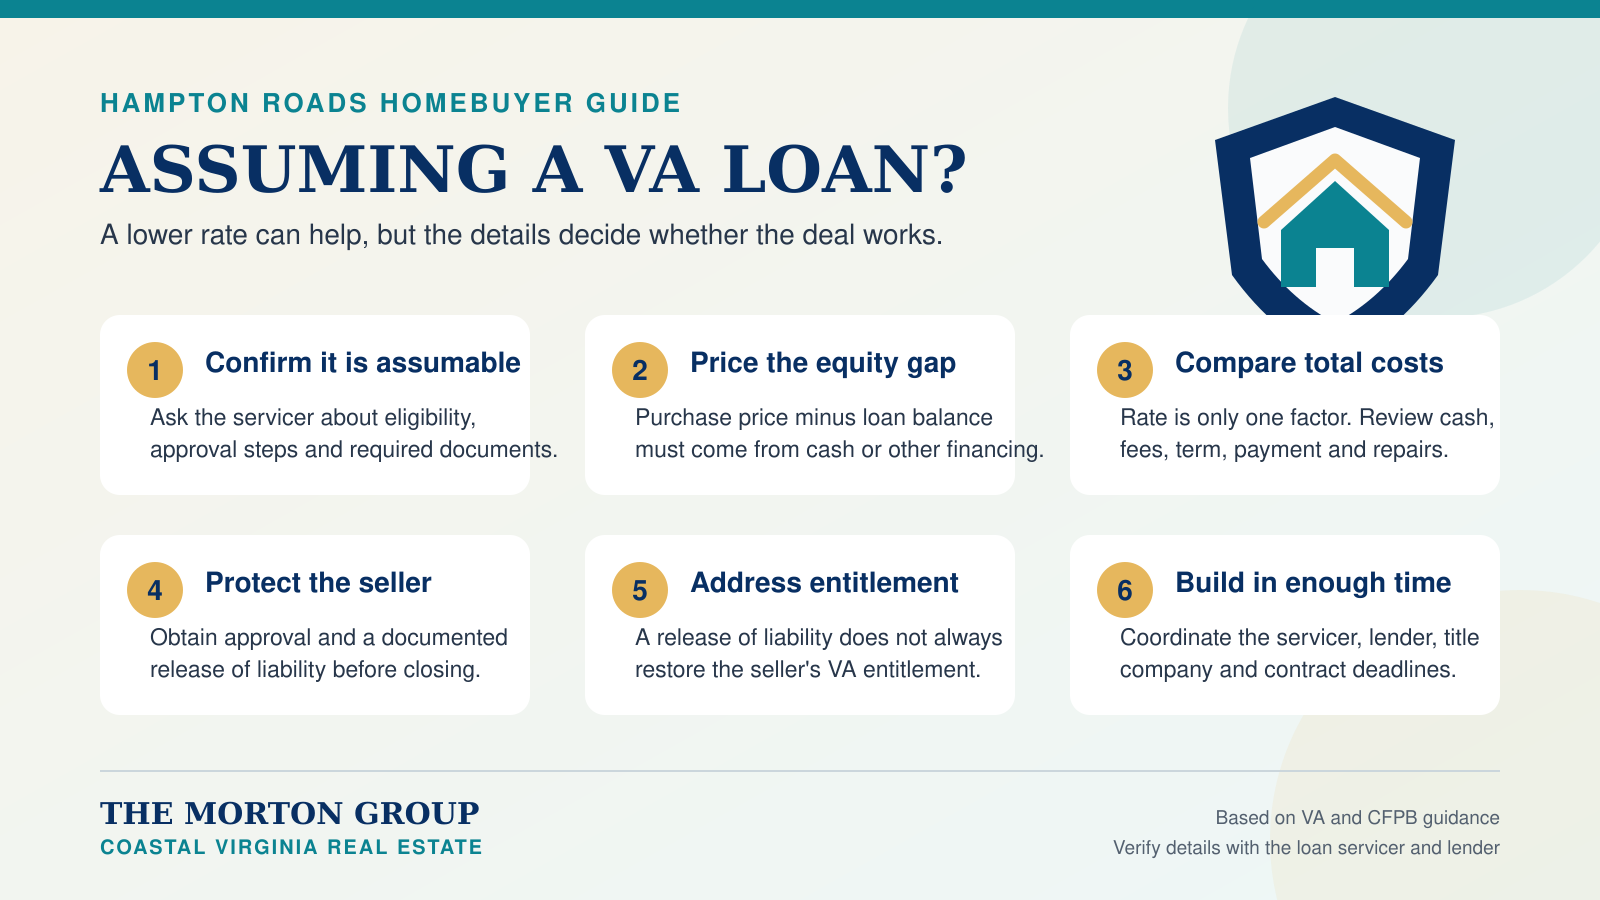
1. Is this specific loan assumable?
Start with the current loan servicer, not a marketing description. Ask whether the loan is eligible, who processes the assumption, which documents are required, and how approval fits the proposed contract schedule. For VA loans committed on or after March 1, 1988, VA guidance says the loan holder or VA must approve the purchaser's creditworthiness.
2. Who can qualify to assume it?
An assumption is not limited to a simple transfer of the payment book. The buyer must meet the applicable credit and income standards. A buyer does not necessarily have to be a Veteran to assume the loan, but Veteran status becomes critical if the parties want to substitute the buyer's VA entitlement for the seller's.
The VA's Assumption Entitlement Acknowledgment says a substitution of entitlement requires an eligible Veteran with a Certificate of Eligibility, sufficient entitlement and the required occupancy intent.
3. How large is the equity gap?
The assumed balance may be much lower than the home's sale price. The difference is the equity gap. A buyer generally needs cash or approved secondary financing to cover it, along with closing costs and any required reserves. Before treating the rate as a bargain, compare the total cash required and the cost and terms of every loan involved.
4. Has the seller received a release of liability?
A seller should not rely on a buyer's promise to make future payments. VA borrower guidance directs sellers to work with the company receiving the mortgage payments and obtain approval before the sale. The seller should also confirm in writing that the assumption includes the appropriate release from liability.
5. What happens to the seller's VA entitlement?
Release from loan liability and restoration of entitlement are separate issues. According to the VA, the seller's entitlement generally remains tied to the loan until it is paid in full unless an eligible Veteran buyer completes a qualifying substitution of entitlement. That can affect how much VA loan benefit the seller has available for another purchase.
Both parties should request a written explanation from the servicer or a VA Loan Specialist rather than assuming the entitlement will be restored automatically.
6. Does the complete deal still make sense?
Compare the assumption with a new-loan alternative using the same purchase price and realistic costs. Review the remaining loan term, principal balance, monthly principal and interest, taxes, insurance, association fees, cash needed, secondary-financing payment and property condition. The CFPB notes that an assumption may allow a buyer to take over a loan on its existing terms, but total costs still determine whether the transaction fits the buyer's budget.
The Hampton Roads takeaway
In a military-connected market, an assumable VA loan can be a meaningful feature for both sides. It can also add coordination among the servicer, lender, agents, title company and settlement attorney. Build the approval process into the contract and avoid advertising a guaranteed payment or savings before the servicer confirms the details.
For broader context on current prices, inventory and buyer leverage, review our latest Hampton Roads real estate market report. If you are evaluating a home with an assumable VA loan, contact The Morton Group to organize the property, contract and lender questions.
Sources
- U.S. Department of Veterans Affairs: VA-backed purchase loans, updated January 7, 2026.
- U.S. Department of Veterans Affairs: VA Form 26-10291, Assumption Entitlement Acknowledgment, March 2024.
- U.S. Department of Veterans Affairs: Rights of VA Loan Borrowers, accessed October 17, 2026.
- Consumer Financial Protection Bureau: Loan Estimate explainer, last modified October 29, 2025.
- Freddie Mac: Primary Mortgage Market Survey archive, October 15, 2026.