


Published by The Morton Group with AtCoastal Realty | Todd Morton, REALTOR and Owner | October 24, 2026
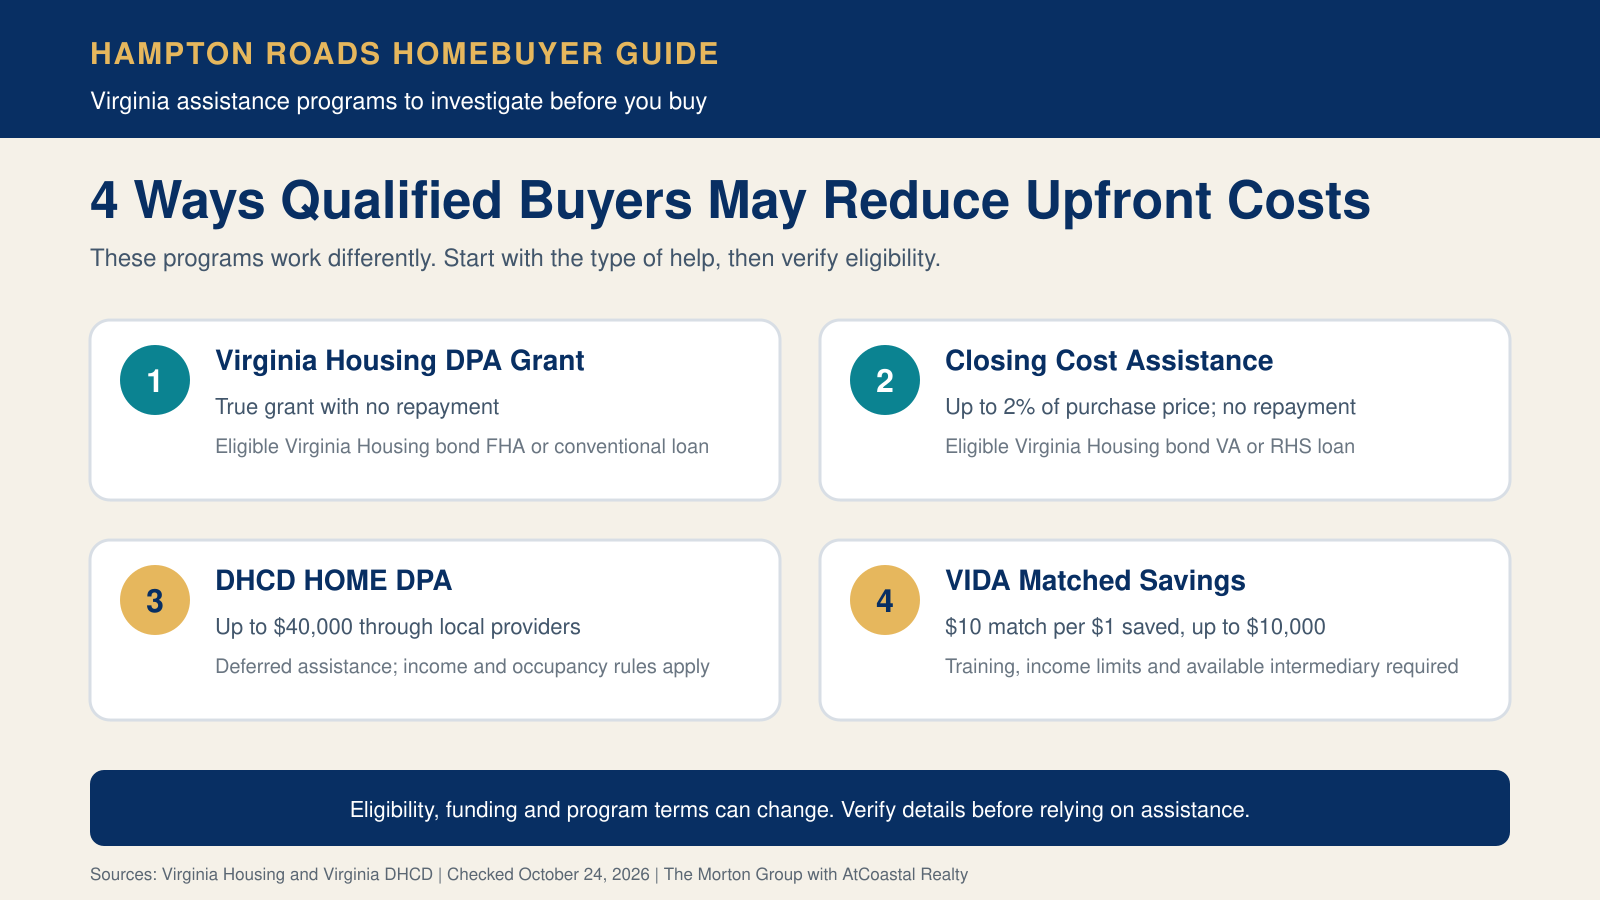
Qualified Hampton Roads buyers may have more than one way to reduce the cash needed at closing. Virginia offers no-repayment grants, deferred assistance delivered through local providers, and a matched-savings program. These programs are not automatic, and availability depends on the buyer, property, loan and funding.
The practical move is to compare assistance before touring homes or writing an offer. A lender or program provider can explain eligibility, timing and whether a particular option works with the financing you plan to use.
Which Virginia homebuyer assistance programs should you compare?
| Program | Type of help | Published feature | Where to start |
|---|---|---|---|
| Virginia Housing DPA Grant | Grant with no repayment | For eligible Virginia Housing bond FHA or conventional loans | Virginia Housing-approved lender |
| Closing Cost Assistance Grant | Grant with no repayment | Up to 2% of the purchase price with eligible bond VA or RHS financing | Virginia Housing-approved lender |
| DHCD HOMEownership DPA | Deferred assistance | Generally up to $40,000 through participating local providers | Approved provider serving the locality |
| VIDA Matched Savings | Savings match | $10 for every $1 saved, up to $10,000 | Participating VIDA intermediary |
Program terms can change, funding may be limited, and the programs may not be combined in every transaction. The table summarizes published program information, not an approval or financing quote.
How are grants different from deferred assistance?
A grant generally does not have to be repaid when its conditions are met. Virginia Housing describes both its Down Payment Assistance Grant and Closing Cost Assistance Grant as true grants with no repayment. The two programs serve different loan combinations: the DPA Grant is tied to eligible bond FHA or conventional financing, while the closing-cost grant is tied to eligible bond VA or Rural Housing Service financing.
The Virginia Department of Housing and Community Development's HOMEownership Down Payment and Closing Cost Assistance works differently. It is delivered through approved local providers and is structured as deferred assistance. The standard program is for qualifying first-time buyers at or below 80% of area median income. Published assistance may cover up to 10% or 15% of the sales price, depending on the approved area, plus up to $2,500 toward closing costs, with a general maximum of $40,000.
VIDA is a savings program rather than money awarded at the closing table without preparation. Eligible participants save for an approved asset and can receive a $10 match for every $1 saved, up to $10,000. The program normally requires financial education, a savings period of four to 24 months and enrollment through a participating intermediary.
What eligibility rules should Hampton Roads buyers expect?
Requirements vary, but buyers should be prepared for income limits, sales-price or loan limits, owner-occupancy rules, property requirements, homebuyer education and use of an approved lender or provider. Some options require first-time-buyer status. Funding and participating providers can also vary by locality.
Do not assume a grant automatically produces the lowest overall cost. Compare the interest rate, monthly payment, mortgage insurance, fees, cash needed at closing and any repayment or occupancy conditions. A program that lowers today's cash requirement may not be the best fit if another loan has better long-term terms.
What should you do before shopping for a home?
- Ask early. Contact an approved lender or program provider before making an offer.
- Verify the full budget. Compare the entire payment and loan terms, not only the down payment.
- Protect your reserves. Plan for inspections, moving expenses, repairs and ownership costs after closing.
- Confirm timing in writing. Learn which documents, classes and approvals must be completed before settlement.
Once your price range and assistance options are confirmed, use our Virginia Beach neighborhood map to compare locations and available homes.
Need a local home-search plan?
We can help you connect the financing conversation to real homes in Virginia Beach and the surrounding Southside Hampton Roads cities. Contact The Morton Group to discuss your search.
Sources
- Virginia Housing: Down Payment Assistance Grant, accessed October 24, 2026.
- Virginia Housing: Closing Cost Assistance Grant, accessed October 24, 2026.
- Virginia Housing: Home Loan Options, accessed October 24, 2026.
- Virginia DHCD: Down Payment Assistance, accessed October 24, 2026.
- Virginia DHCD: Virginia Individual Development Accounts, accessed October 24, 2026.