Hampton Roads Real Estate Blog

Explore real estate advice for Virginia Beach, Norfolk, Chesapeake and the surrounding Hampton Roads communities. Browse articles on buying, selling, neighborhoods and housing market developments from The Morton Group with AtCoastal Realty.

Looking for a location to start your search? Visit our Virginia Beach neighborhood maps or ask us about your next move.

Aug. 25, 2025

From Frenzy to Breathing Room: Virginia Beach Home Buyers Finally Have Time Again


If you tried to buy a home a few years ago, you probably still remember the frenzy. Homes were listed one day and gone the next. Sometimes it only took hours. You had to drop everything to go and see the house, and if you hesitated even slightly, someone else swooped in and bought it – sometimes even sight unseen.

That kind of intensity pushed a lot of buyers to the sidelines. It was stressful, chaotic, and for many, really discouraging.

But here’s what you need to know: those days are behind us.

Today’s market is moving slower, in the best possible way. And that’s creating more opportunity for buyers who felt shut out in recent years.

The Stat That Changes Everything

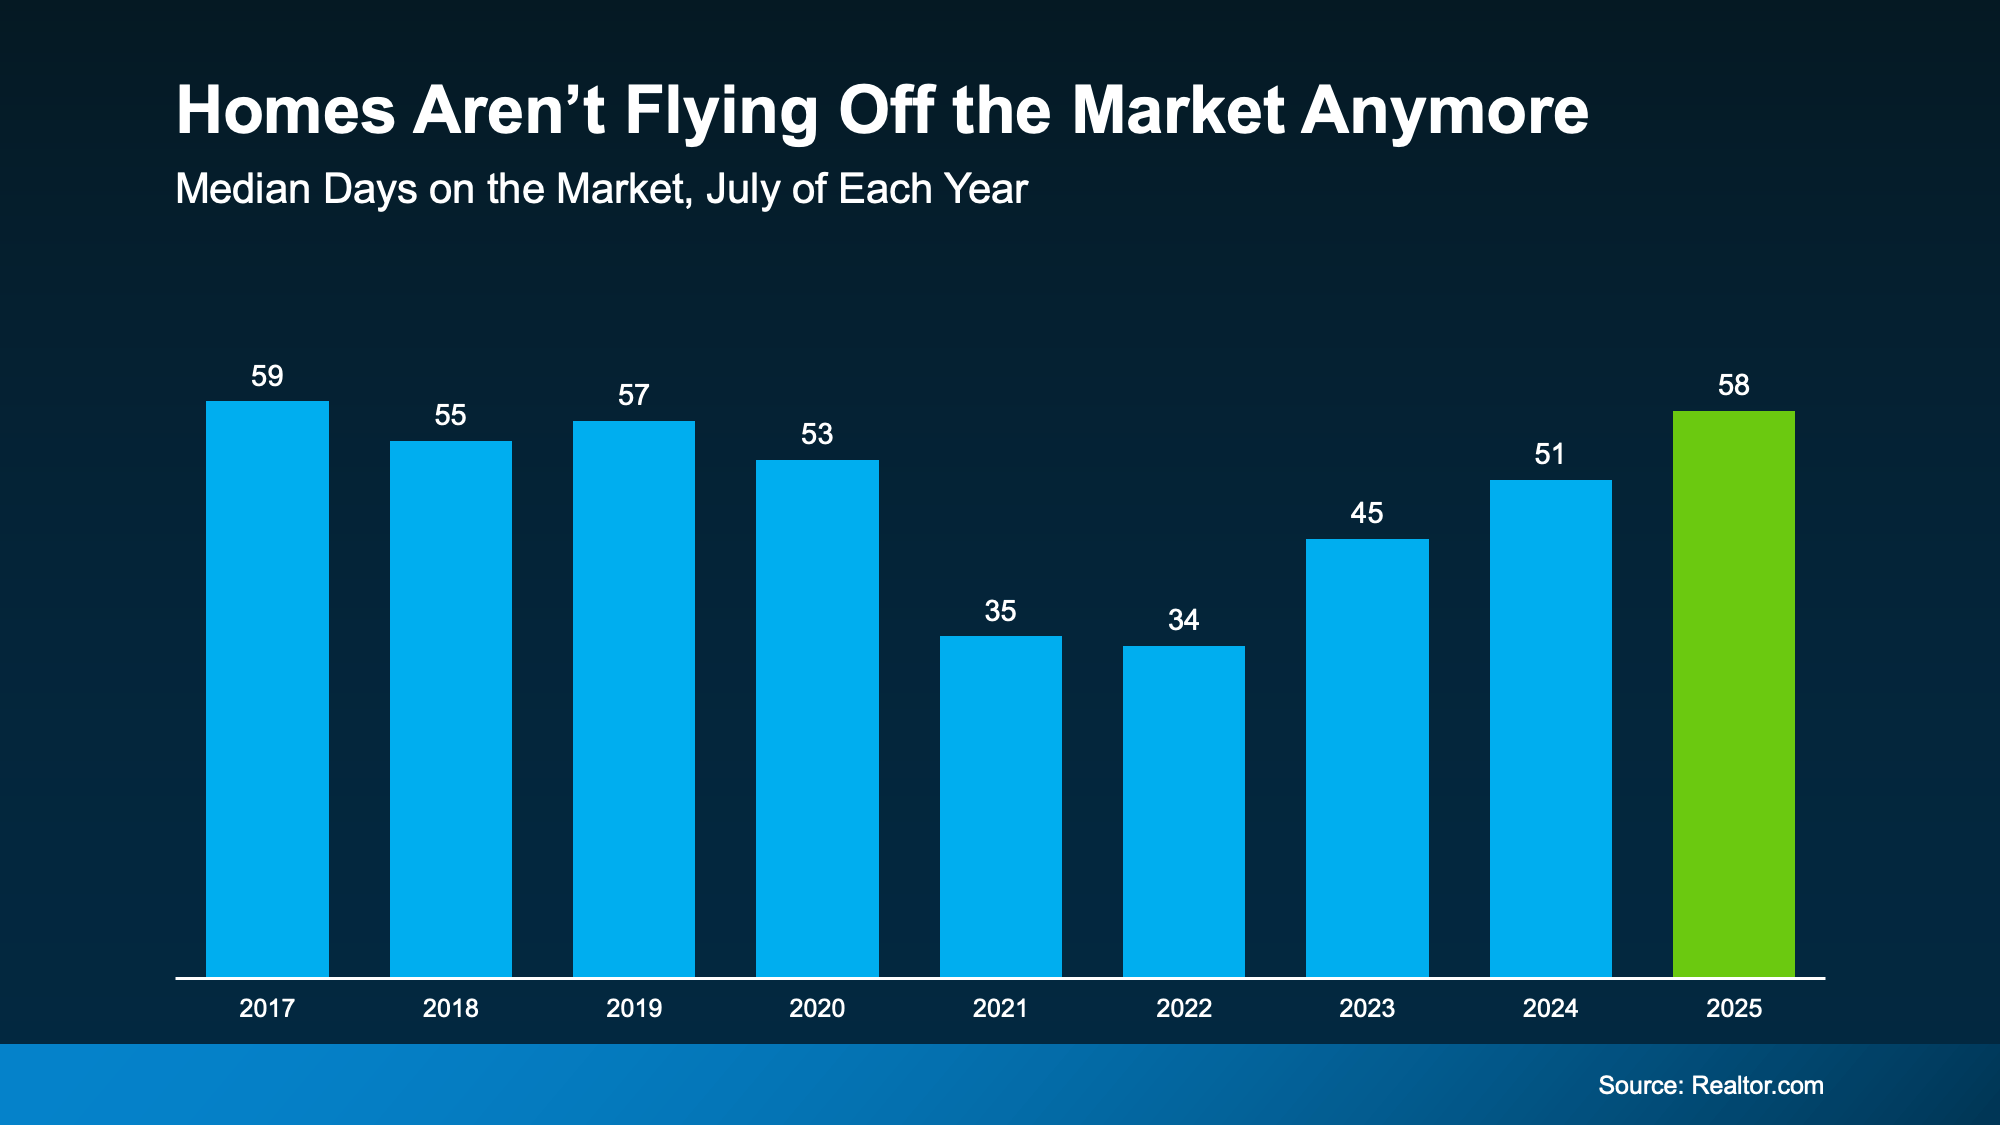
According to the latest data, homes are spending an average of 58 days on the market. That’s much more normal. And it’s a big improvement compared to the height of the pandemic, when homes were flying off the shelves in a matter of days (see graph below):
a graph of blue bars with white text

That means you now have more time to make decisions than you have at any point in the past five years. And that’s a big deal. Now, you’ve got:

Time to think.

Time to negotiate.

Time to make a smart move without all the pressure.

More Time Means Less Stress (and More Leverage)

Based on the data in the graph above, you have an extra week to decide compared to last year. And nearly double the time you would have had at the market’s peak.

Back then, fear of missing out drove buyers to act fast, sometimes too fast. Today, the pace is slower, which means you’re in control. As Bankrate puts it:

“For years, buyers have been racing to snag homes because of the fierce competition. But the market’s cooled off a bit now, and that gives buyers some breathing room. Homes are staying listed longer, so buyers can slow down, weigh their options and make more confident decisions.”

With more homes on the market and fewer buyers racing to grab them, the balance has shifted. Bidding wars aren’t as common, and that means you may have room to negotiate. And you can actually take a breath before you make your decision.

More listings + a slower pace = less stress and more opportunity

But, and this is important, it still depends on where you’re buying. Nationally, homes are moving slower. But your local market sets your real pace. Some states are moving faster than others. It may even vary down to the specific zip code or neighborhood you’re looking at. And that’s why working with an agent to know what’s happening in your area is more important than ever. 

To see how your state compares to the national average (58 days), check out the map below:
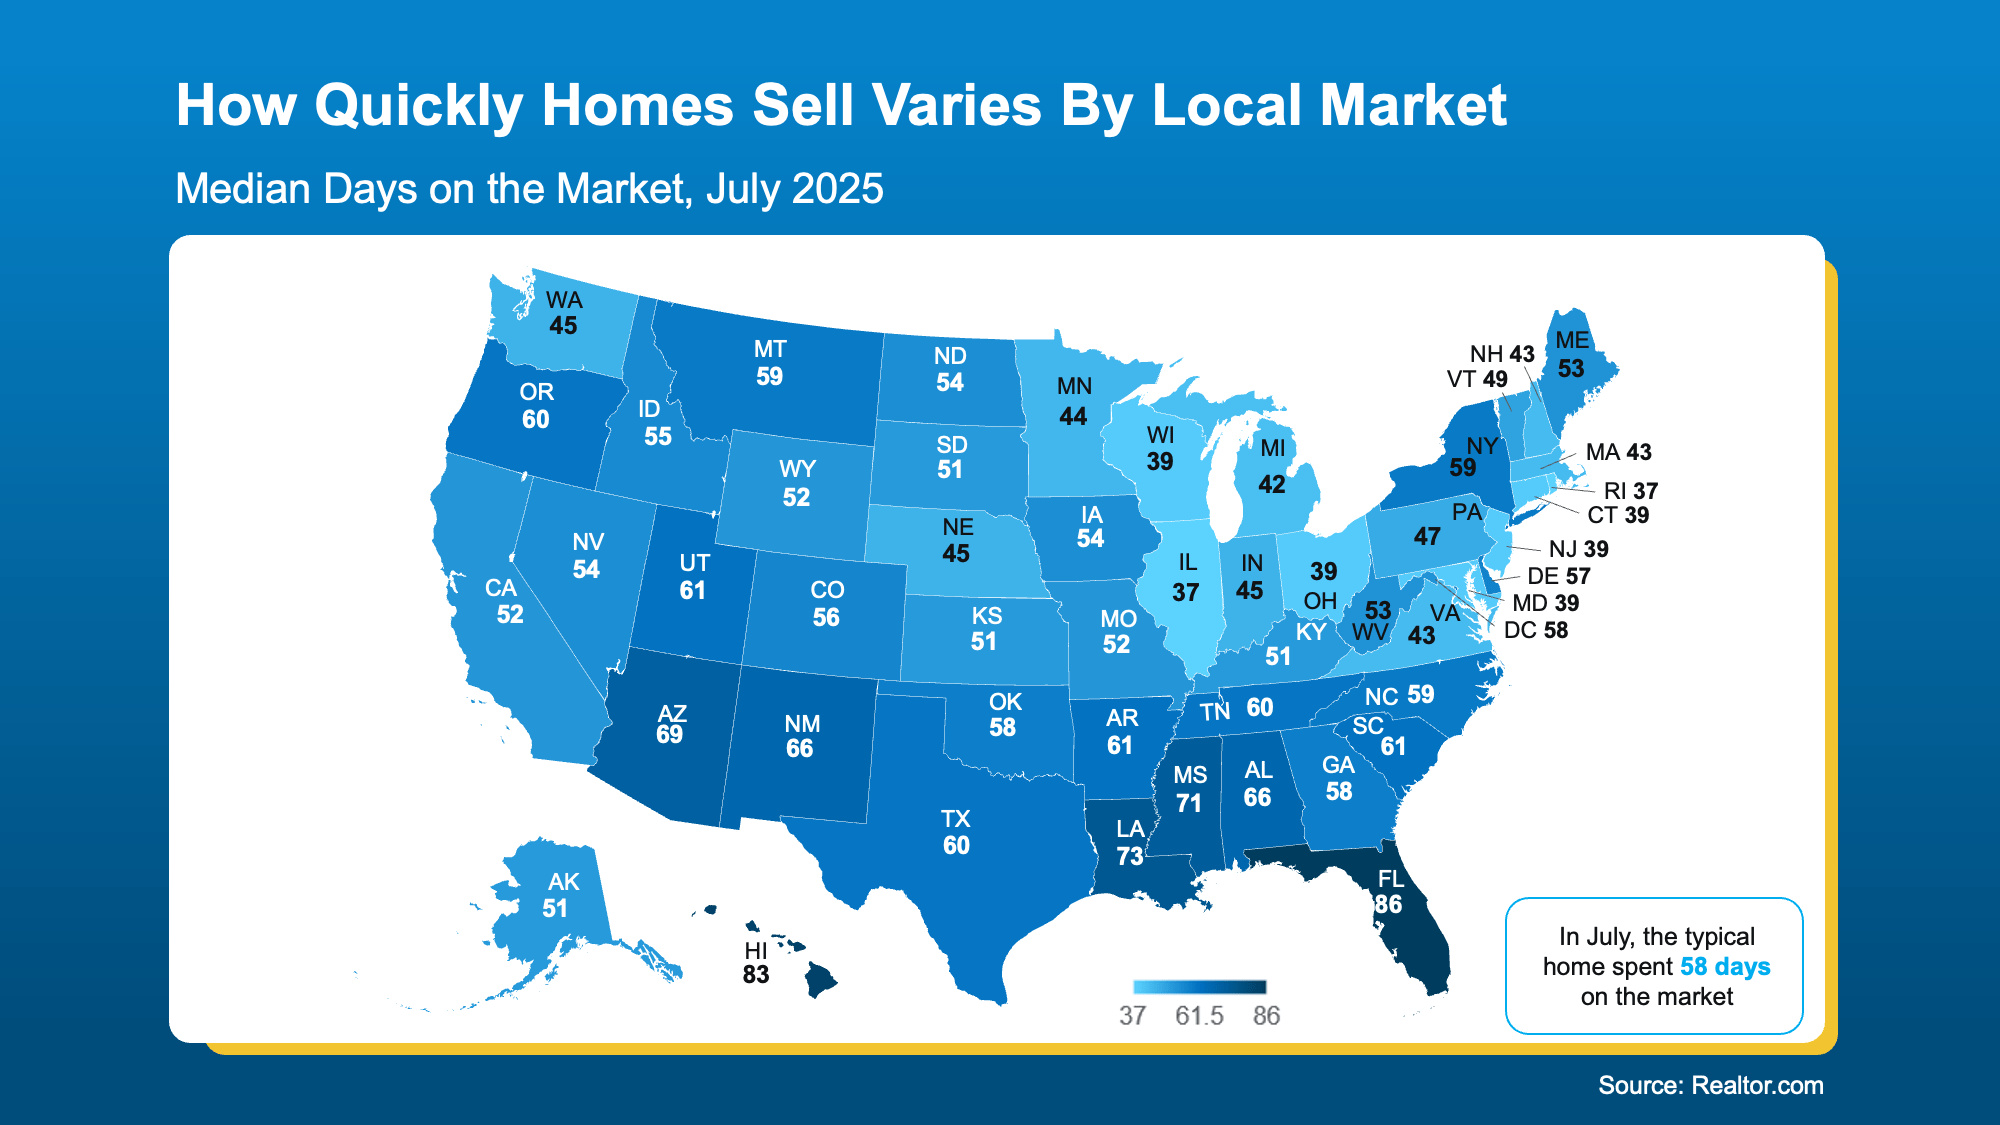
a map of the united states

As Realtor.com explains:

“While national headlines might suggest a buyer’s market is taking hold, the reality on the ground depends heavily on where and what you’re trying to buy. Local trends can diverge sharply from national averages, especially when you factor in price range, property type, and post-pandemic market dynamics.”

A smart local agent can tell you exactly when to move fast and when you can take your time, so you never miss the right home for you.

Bottom Line

If the chaos of the past few years drove you to hit pause, this is your green light. The market’s pace has shifted. You have more time. More options. More power.

And with the right agent guiding you, you’re in the best position you’ve been in for years.

Let’s talk about what the pace looks like in our area, and if now could be the right time for you to re-enter the market.
Posted in Buying
Aug. 21, 2025

Virginia Beach Condos Could Be a Win for Today’s Buyers


Not every homebuyer wants the biggest house on the block. Some want something simpler, more affordable, and easier to maintain, especially in a market where every dollar counts. That’s where condos come in.

For first-time buyers, they can be a smart way to get into homeownership without stretching your budget. For downsizers, they offer less space to maintain with the flexibility to stay in a great location.

And right now, condos are one of the most buyer-friendly parts of the market.

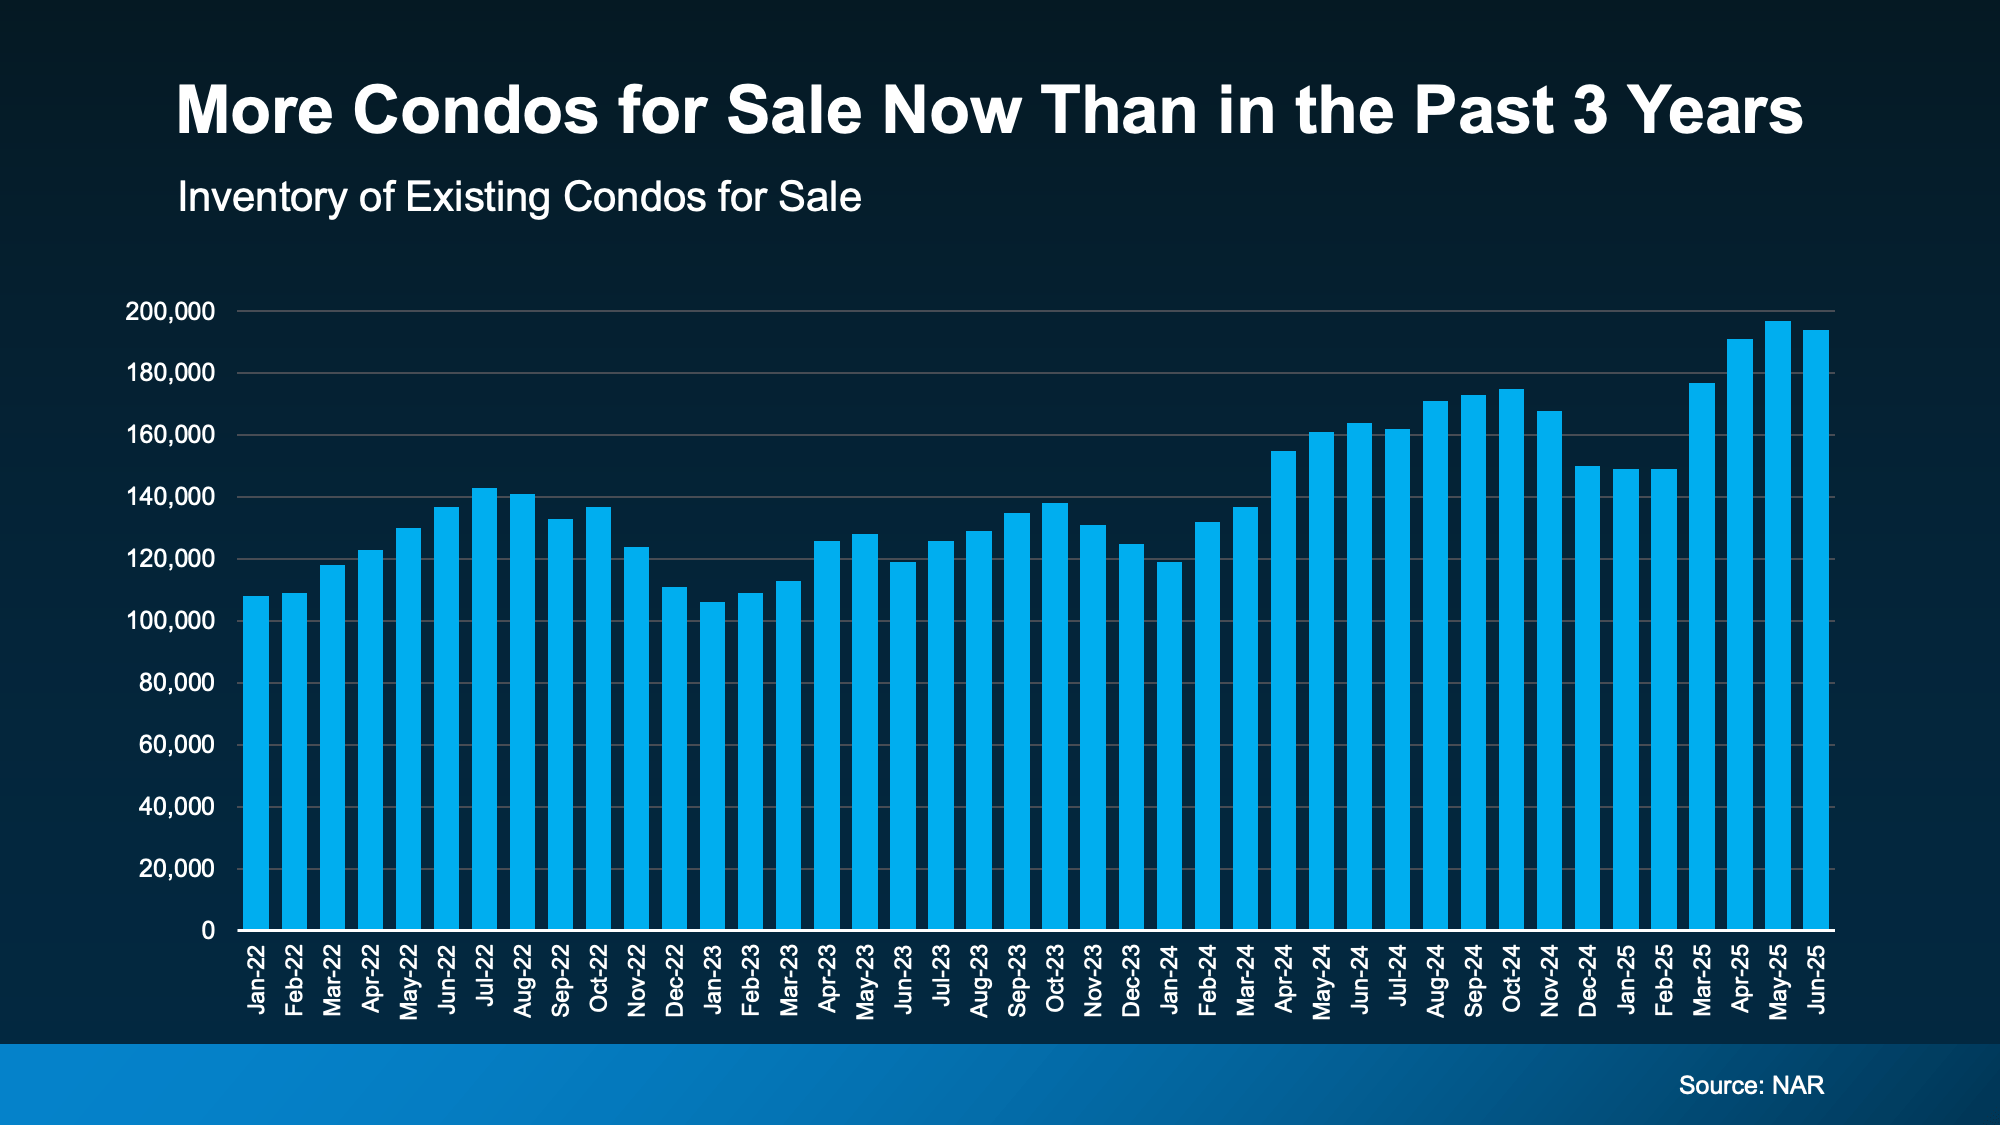
Condo Inventory Is Up, And That Means More Choice

According to the National Association of Realtors (NAR), there are 194,000 condos for sale right now. That’s the second highest amount we’ve seen in the last three years (see graph below):

a graph of blue lines with white text

Just remember, this is the national figure. The exact number is going to vary based on where you’re looking to buy. But, generally speaking, you have more options and less competition.

You’re not stuck waiting for something to pop up or rushing into an offer just to beat someone else to it. You’ve got plenty to choose from. And if you’re particular about layout, location, or amenities, this is your chance to be selective.

That’s a big shift from the market frenzy of just a few years ago. Compared to early 2022, we’ve got nearly double the condos available now. That gives you more breathing room to find the right fit.

Prices Are Cooling, and Buyers Hold More Negotiating Power

And since there are more for sale, many sellers are more open to negotiating right now. So, you may be able to get a better price. As Redfin explains:

“. . . condo buyers in many cities may be able to find sellers who are willing to give concessions and/or sell for less than their asking price.”

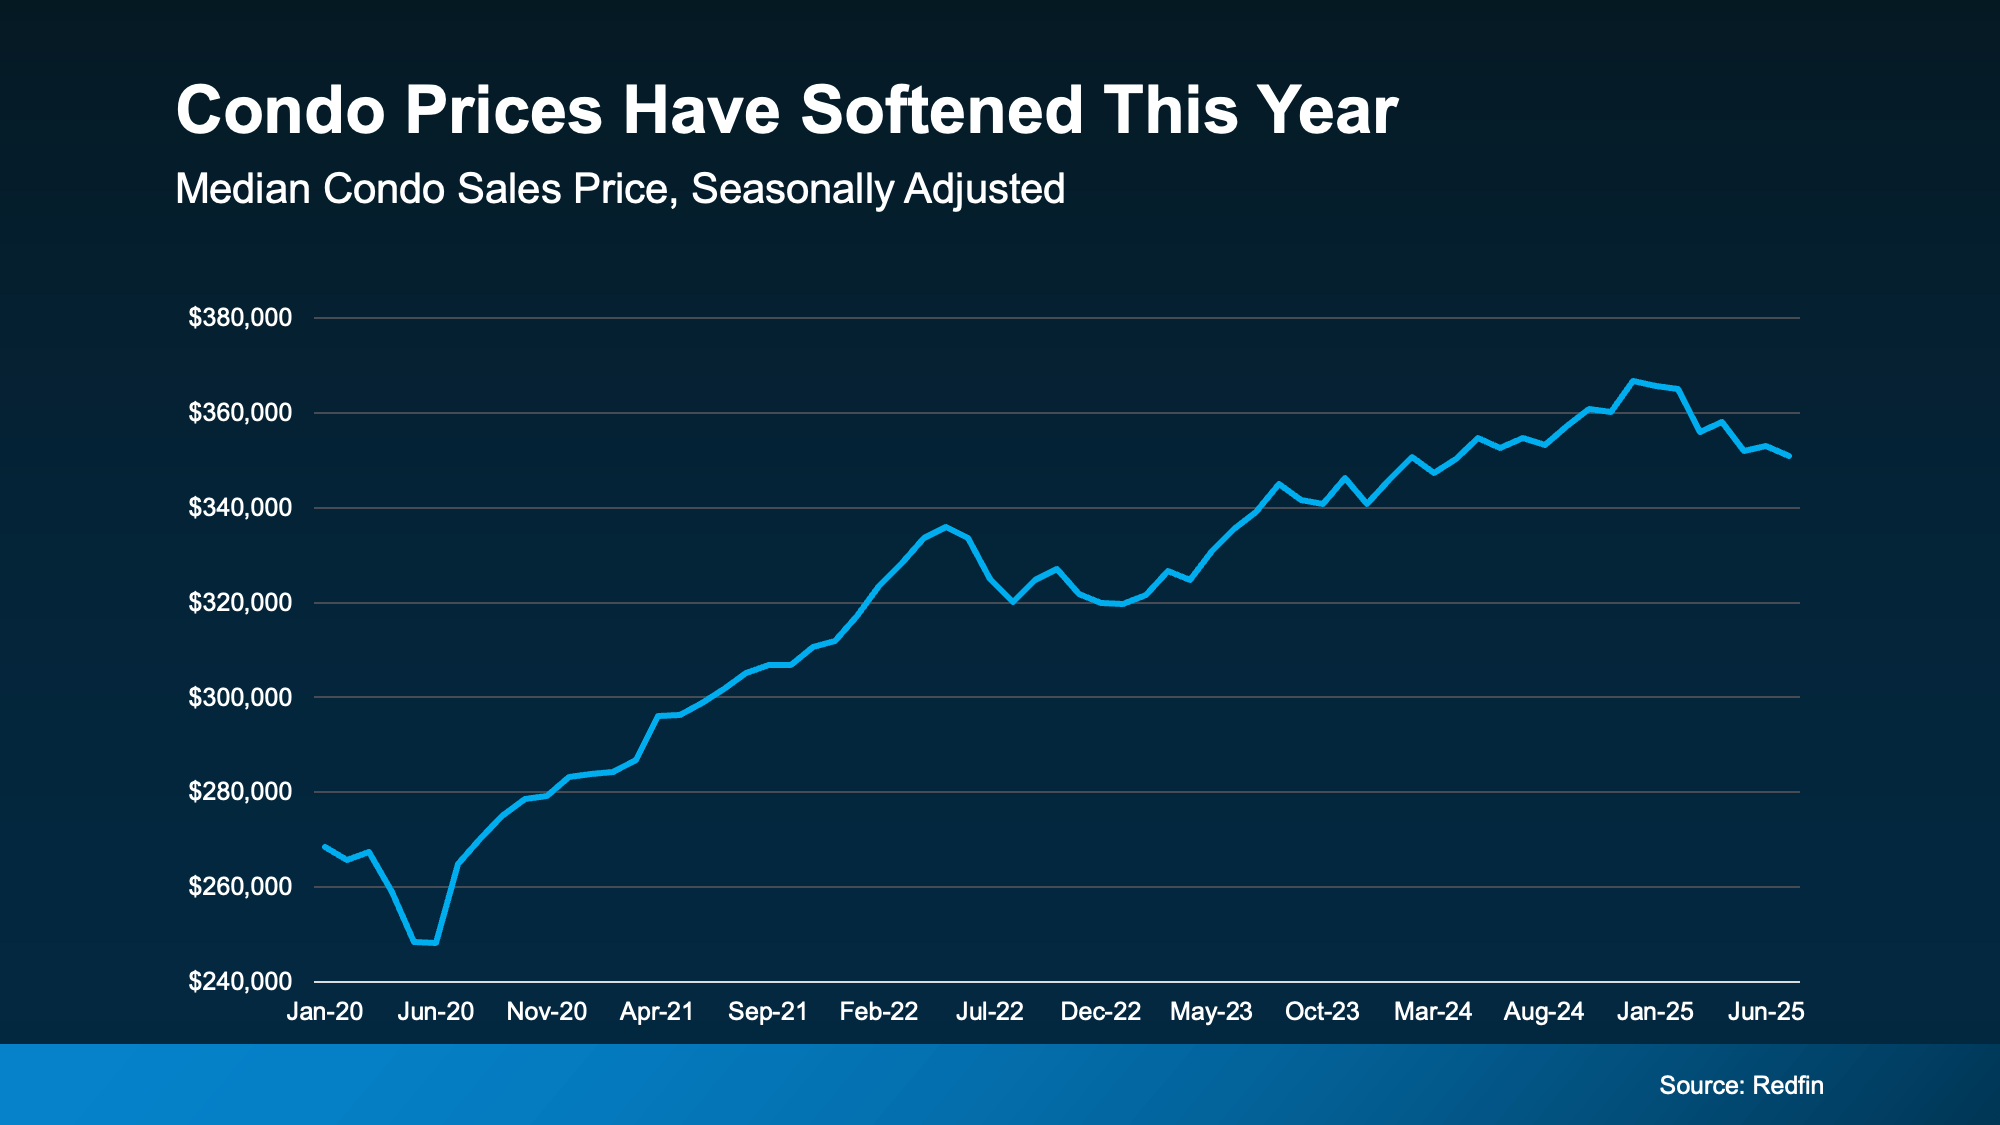
Condo prices are starting to ease in many markets. According to Intercontinental Exchange (ICE), condo prices dipped 1.3% in June compared to last year. And over half of the top 100 U.S. metros saw condo prices drop slightly year-over-year.

Data from Redfin shows what the recent dip in prices looks like (see graph below):

a graph showing the price of a sales increase

That doesn’t just help with affordability, it also shifts the power dynamic. Condo buyers in many markets are now in a position to negotiate on price and ask for concessions, like help with closing costs.

Bottom Line

Condos aren’t just a fallback option. In today’s market, they’re one of the most strategic ways to buy. With more options, softening prices, and more room to negotiate, now could be the right time to make your move.

Could a condo check more boxes than you expected? Let’s talk through your options and find out.

Posted in Buying
Aug. 18, 2025

Is It Better To Buy Now or Wait for Lower Mortgage Rates? Here’s the Tradeoff


Mortgage rates are still a hot topic – and for good reason. After the most recent jobs report came out weaker than expected, the bond market reacted almost instantly. And, as a result, in early August mortgage rates dropped to their lowest point so far this year (6.55%).

While that may not sound like a big deal, pretty much every buyer has been waiting for rates to fall. And even a seemingly small drop like this reignites the hope we’re finally going to see rates trending down. But what’s realistic to expect?

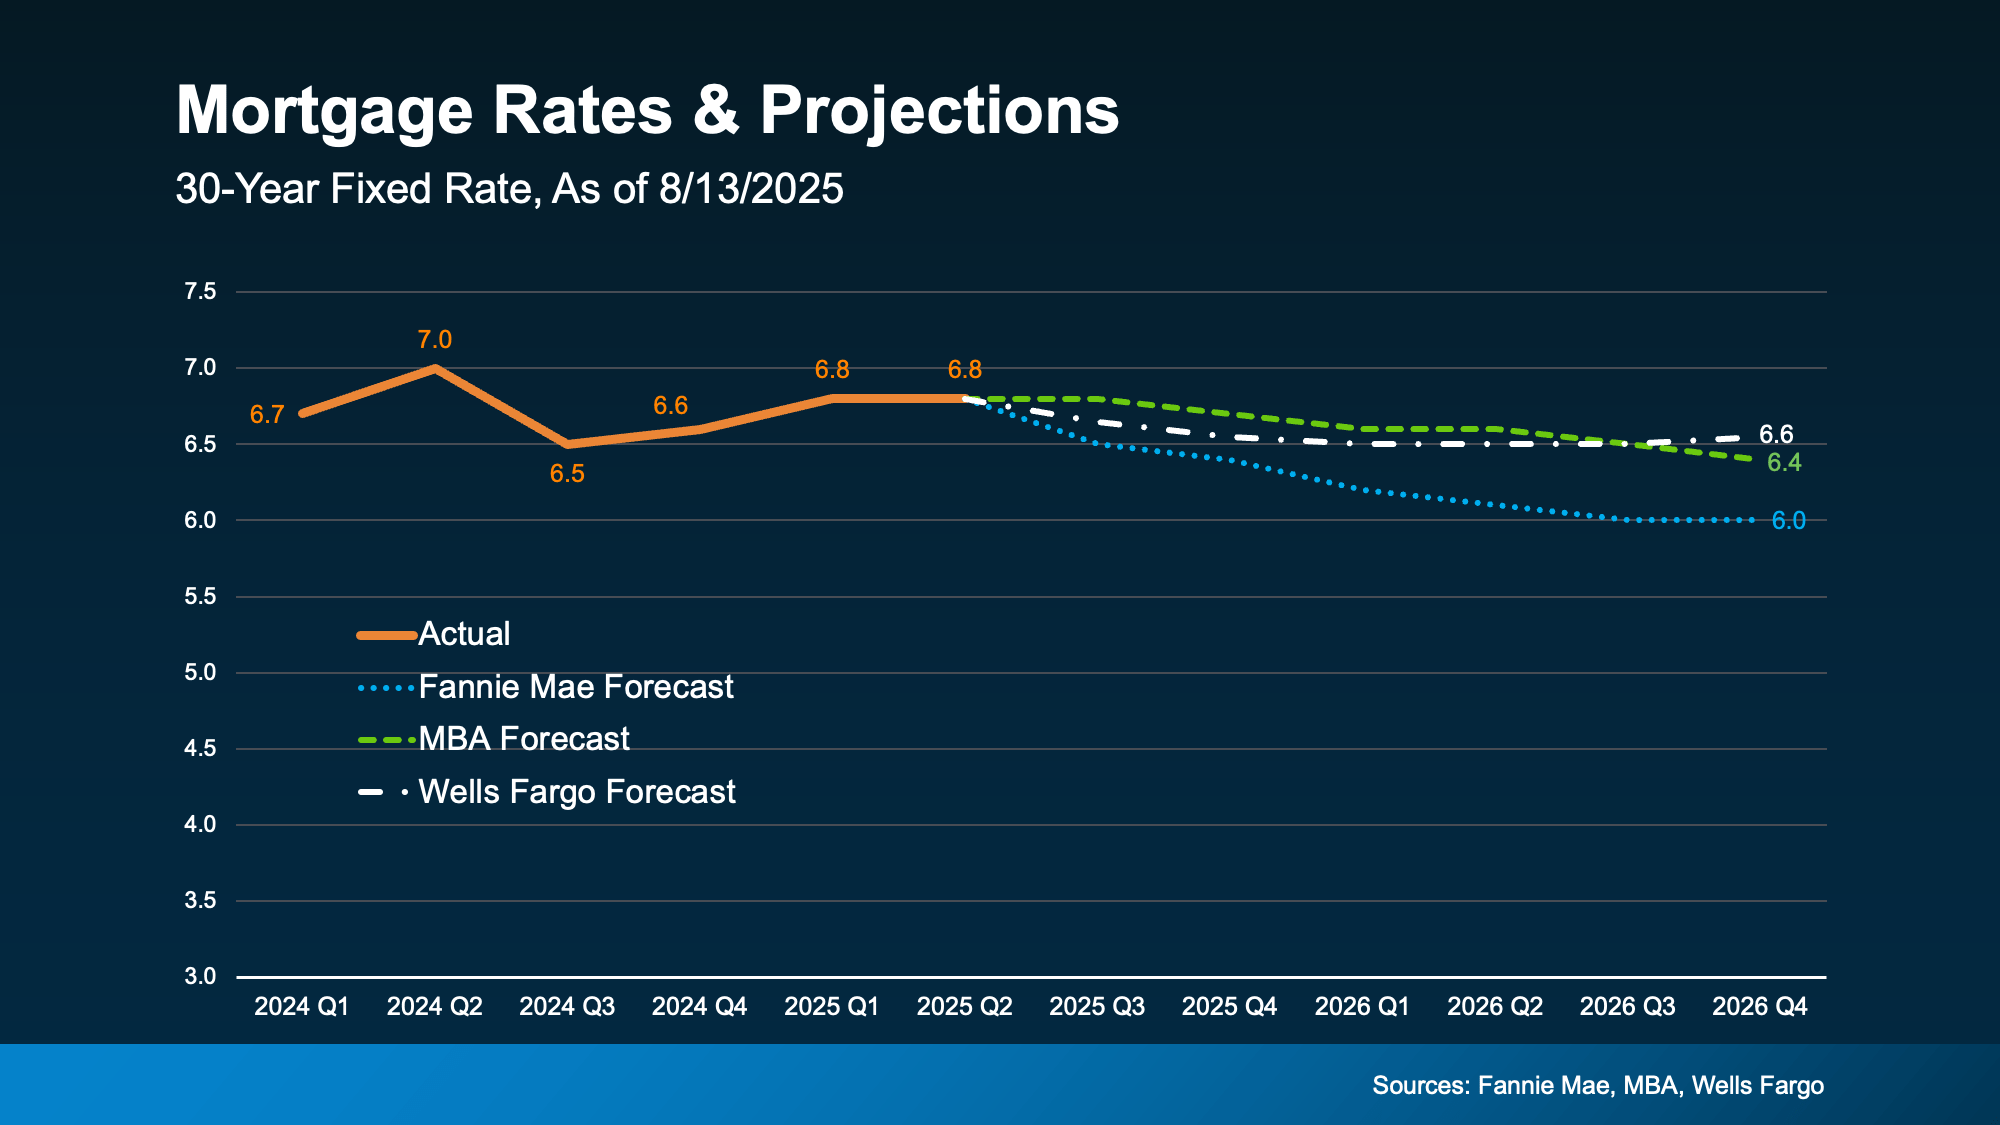
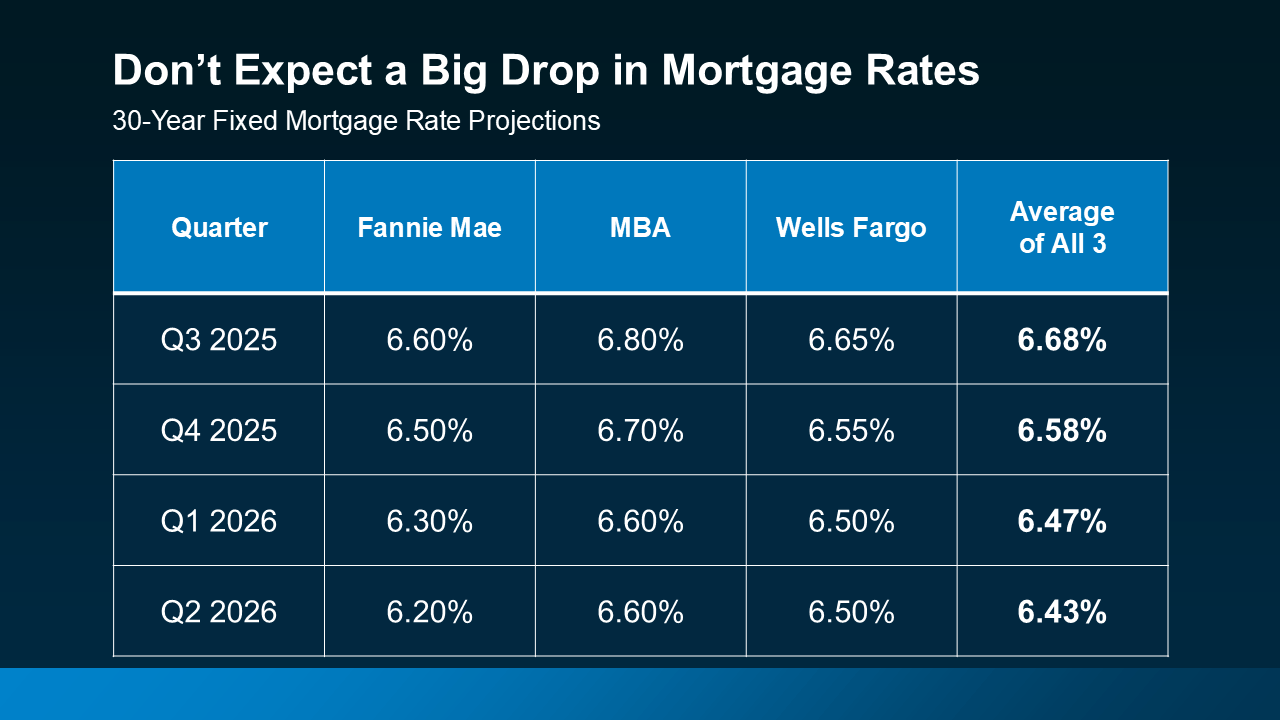
According to the latest forecasts, rates aren’t expected to fall dramatically anytime soon. Most experts project they’ll stay somewhere in the mid-to-low 6% range through 2026 (see graph below):

a graph with numbers and lines

In other words, no big changes are expected. But small shifts, like the one we just saw, are still likely. 

Each time there’s changing economic news, there’s a chance mortgage rates will react. And with so many reports coming out this week, we’ll get a better feeling of where the economy and inflation are headed – and how rates will respond.

What Rate Would Get Buyers Moving Again?

The magic number most buyers seem to be watching for is 6%. And it’s not just a psychological benchmark; it has real impact. A recent report from the National Association of Realtors (NAR) says if rates reach 6%:

  • 5.5 million more households could afford the median-priced home
  • And roughly 550,000 people would buy a home within 12 to 18 months

That’s a lot of pent-up demand just waiting for the green light. And if you look back at the graph above, you’ll see Fannie Mae thinks we’ll hit that threshold next year. That raises an important question: Does it really make sense to wait for lower rates?

Because here’s the tradeoff. If you’re waiting for 6%, you need to realize a lot of other people are too. And when rates do continue to inch down and more buyers jump into the market all at once, you could face more competition, fewer choices, and higher home prices. NAR explains it like this:

"Home buyers wishing for lower mortgage interest rates may eventually get their wish, but for now, they’ll have to decide whether it’s better to wait or jump into the market."

Consider the unique window that exists right now:

  • Inventory is up = more choices
  • Price growth has slowed down = more realistic pricing
  • You may have more room to negotiate = you could get a better deal

These are all opportunities that will go away if rates fall and demand surges. That’s why NAR says:

"Buyers who are holding out for lower mortgage rates may be missing a key opening in the market."

Bottom Line

Rates aren't expected to hit 6% this year. But when they do, you’ll have to deal with more competition as other buyers jump back in. If you want less pressure and more negotiating power, that opportunity is already here – and it might not last for long. It all depends on what happens in the economy next.

Let’s talk about what’s happening in our area and whether it makes sense to make your move now, before everyone else does.

Posted in Buying, Market Updates
Aug. 14, 2025

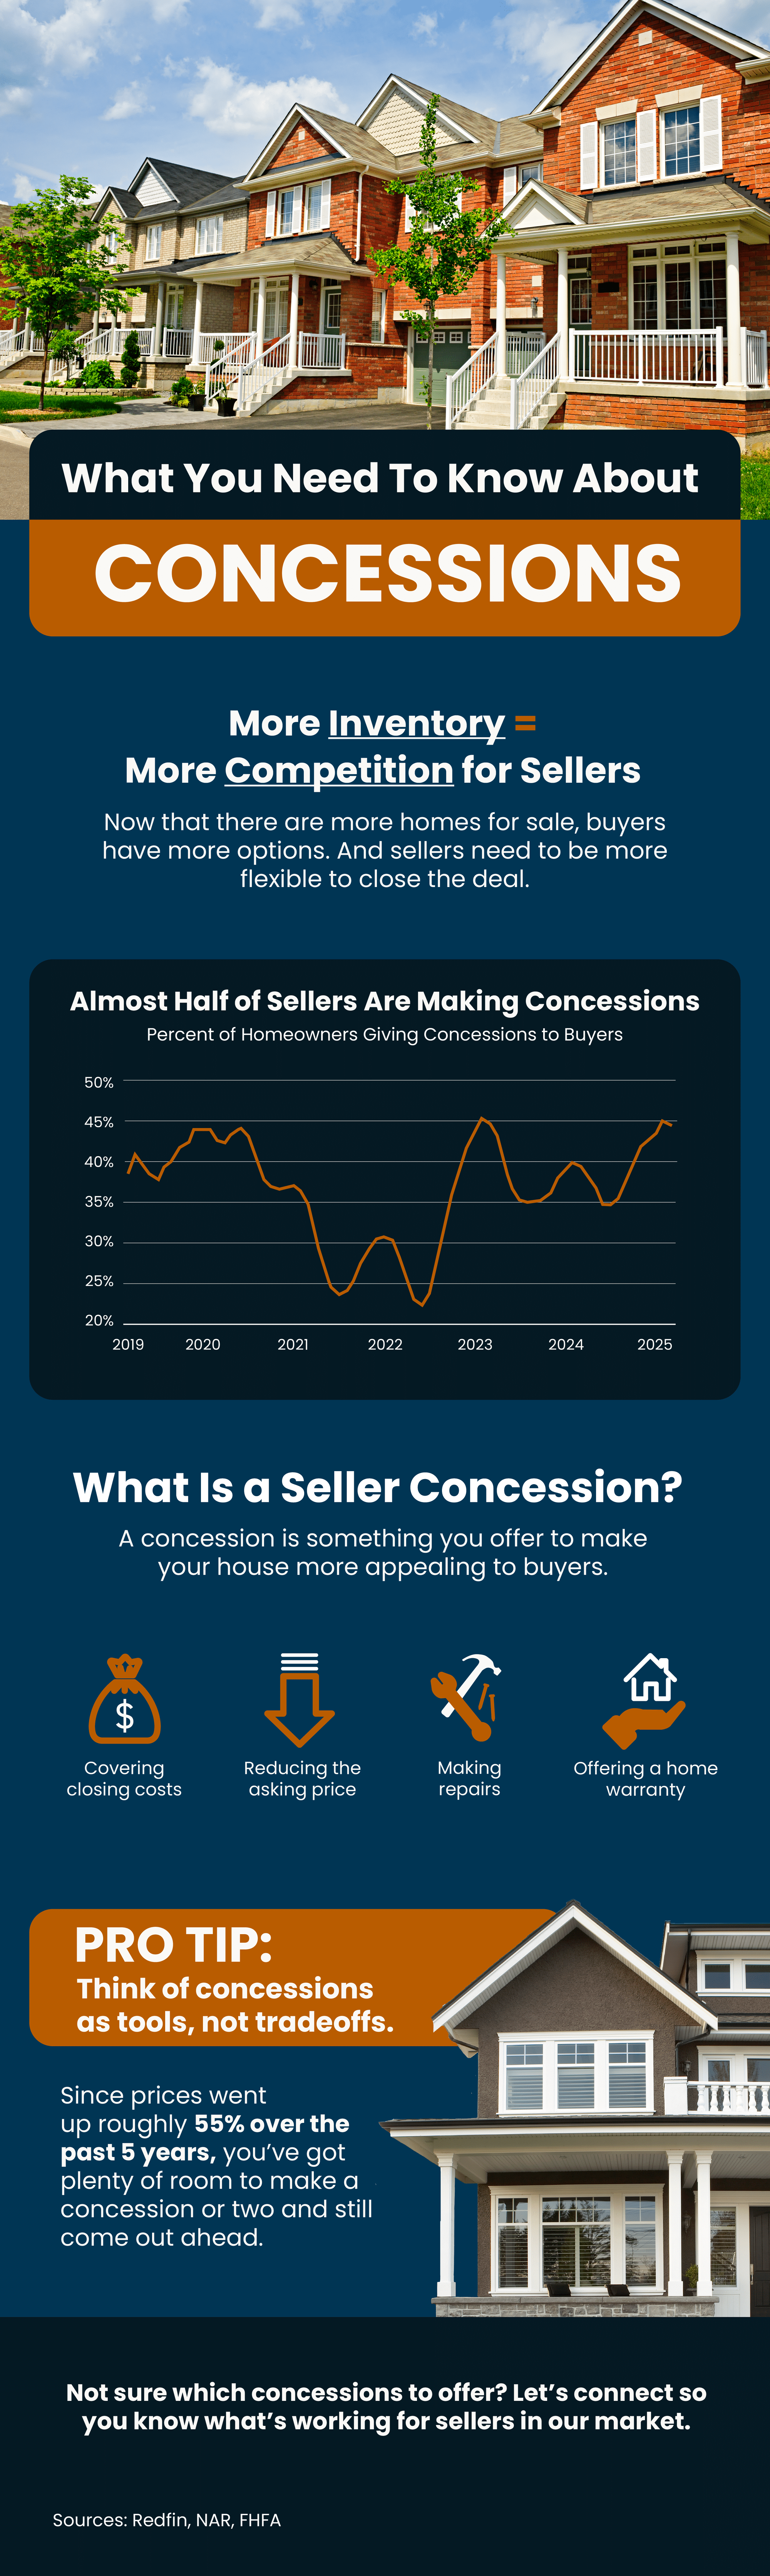
What You Need To Know About Concessions When Buying A Home - Infographic

Now that there are more homes for sale, buyers have more options. And sellers need to be more flexible to close the deal. That's why almost half of homeowners are making some type of concession. This can include covering closing costs, paying for repairs, or dropping the price.

What You Need To Know About Concessions When Selling a Home

Not sure which concessions to offer? Let’s connect so you know what’s working for sellers in our market.

Posted in Selling
Aug. 11, 2025

Virginia Beach Homes Listed With an Agent Sell for More

Selling your house without an agent might feel like a shortcut (and a money saver)… until it costs you thousands. Last year, on average, homes sold in Virginia Beach (and Nationally) with an agent went for 15% more than those that sold without the help of an agent. And here's why the gap is so big. The market is balancing out. There are more homes for buyers to choose from right now, and that means the strategies that worked a year or two ago won’t work today. The Morton Group have the skills and experience to sell in a shifting market. And if you try to sell without that expertise, chances are you’re going to feel it in your bottom line. So, before you decide to tackle it on your own, let’s have a quick conversation about what’s changing and what’s working right now so you don’t leave money on the table.

Selling your house without an agent might feel like a shortcut (and a money saver)… until it costs you thousands.  Last year, on average, homes sold with an agent went for 15% more than those that sold without the help of an agent

#SellYourHouse #HomeSellingTips #TheMortonGroup #virginiabeach

Posted in Selling
Aug. 7, 2025

A Second Home Might Be the Missing Piece in Your Retirement Plan


Are you wondering if you’re on track to retire someday?

According to Intuit, 69% of people say today’s financial environment makes it tough to plan for the future, and 68% aren’t sure they’ll ever be able to retire. That’s why many people are exploring new ways to build stability and long-term income.

And that’s where real estate comes in.

Why Real Estate? Here’s What It Can Do for You

If you’re able to make the numbers work, buying a second home can be a powerful tool for your future retirement. It could help you:

  • Build wealth over time: As home prices rise through the years, your second home should grow in value and increase your net worth.
  • Generate extra income: Renting the home could bring in some extra income you can add to your existing retirement savings. Just remember, some of the rent coming in will need to be used to pay that mortgage and maintain that house. 
  • Profit in the future: You may decide to sell the second home down the road and use the profit from that sale to give your retirement funds a boost.
  • Diversify your financial assets: Real estate offers a tangible asset that can help reduce your dependence on just stocks or savings, making your overall financial picture more stable.

Most Second Homeowners Aren’t Big Investors

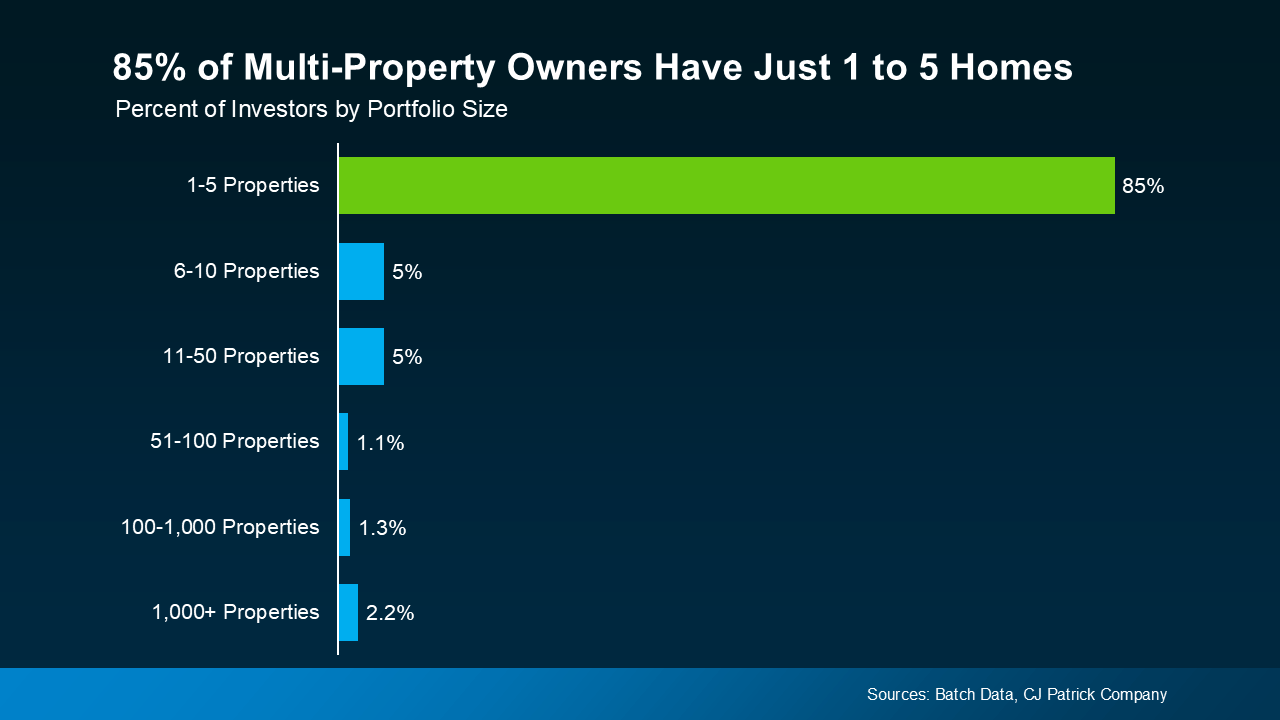
And if you’re thinking: wait, owning multiple homes is only for big investors – data shows that's not necessarily true. Many homeowners who buy an additional property aren’t the big investors you hear so much about. They’re people like your neighbors.

In fact, data from BatchData and CJ Patrick Company shows 85% of people who own more than one property have just 1 to 5 homes (see graph below):

a screenshot of a graph

That means most who own multiple homes are people (not large investors) who’ve bought an extra home to rent out or hold onto for later.

Why Now Might Be the Right Time

And right now, the door may be opening for buyers like you. According to Danielle Hale, Chief Economist at Realtor.com:

“. . . the balance of power in the housing market keeps shifting in favor of homebuyers. . . A confluence of factors—including more homes for sale, rising price cuts, and slower-moving inventory—is giving buyers more leverage than they've had in years . . .”

If you live in an area where home prices are expected to rise, buying another property now and selling it later could help fund your future. Or you could rent it out and earn income now.

Start with Just a Few Trusted Pros

If this idea sounds interesting, the most important first step is to connect with a few key people who can guide you through the process:

  • A local real estate agent who understands the market
  • A lender who specializes in second home or investment loans

Surrounding yourself with the right pros can help you make confident decisions from day one.

Bottom Line

Let’s talk about what’s possible and explore whether owning a second home could bring you more security and peace of mind for the road ahead.

If a second home could help you retire earlier or with more freedom, would you want to take a closer look?

Posted in Buying, Market Updates
Aug. 4, 2025

The Truth About Down Payments (It’s Not What You Think)


Buying a home is exciting… until you start thinking about the down payment. That’s when the worry can set in.

“I’ll never save enough.”

“I need a small fortune just to get started.”

“I guess I’ll just rent forever.”

Sound familiar? You’re not alone. And you’re definitely not out of luck.

Here’s the thing: a lot of what you’ve heard about down payments just isn’t true. And once you know the facts, you might realize you’re a lot closer to owning a home than you think.

Let’s break it all down and bust some big down payment myths while we’re at it.

Myth 1: “I need to come up with a big down payment.”

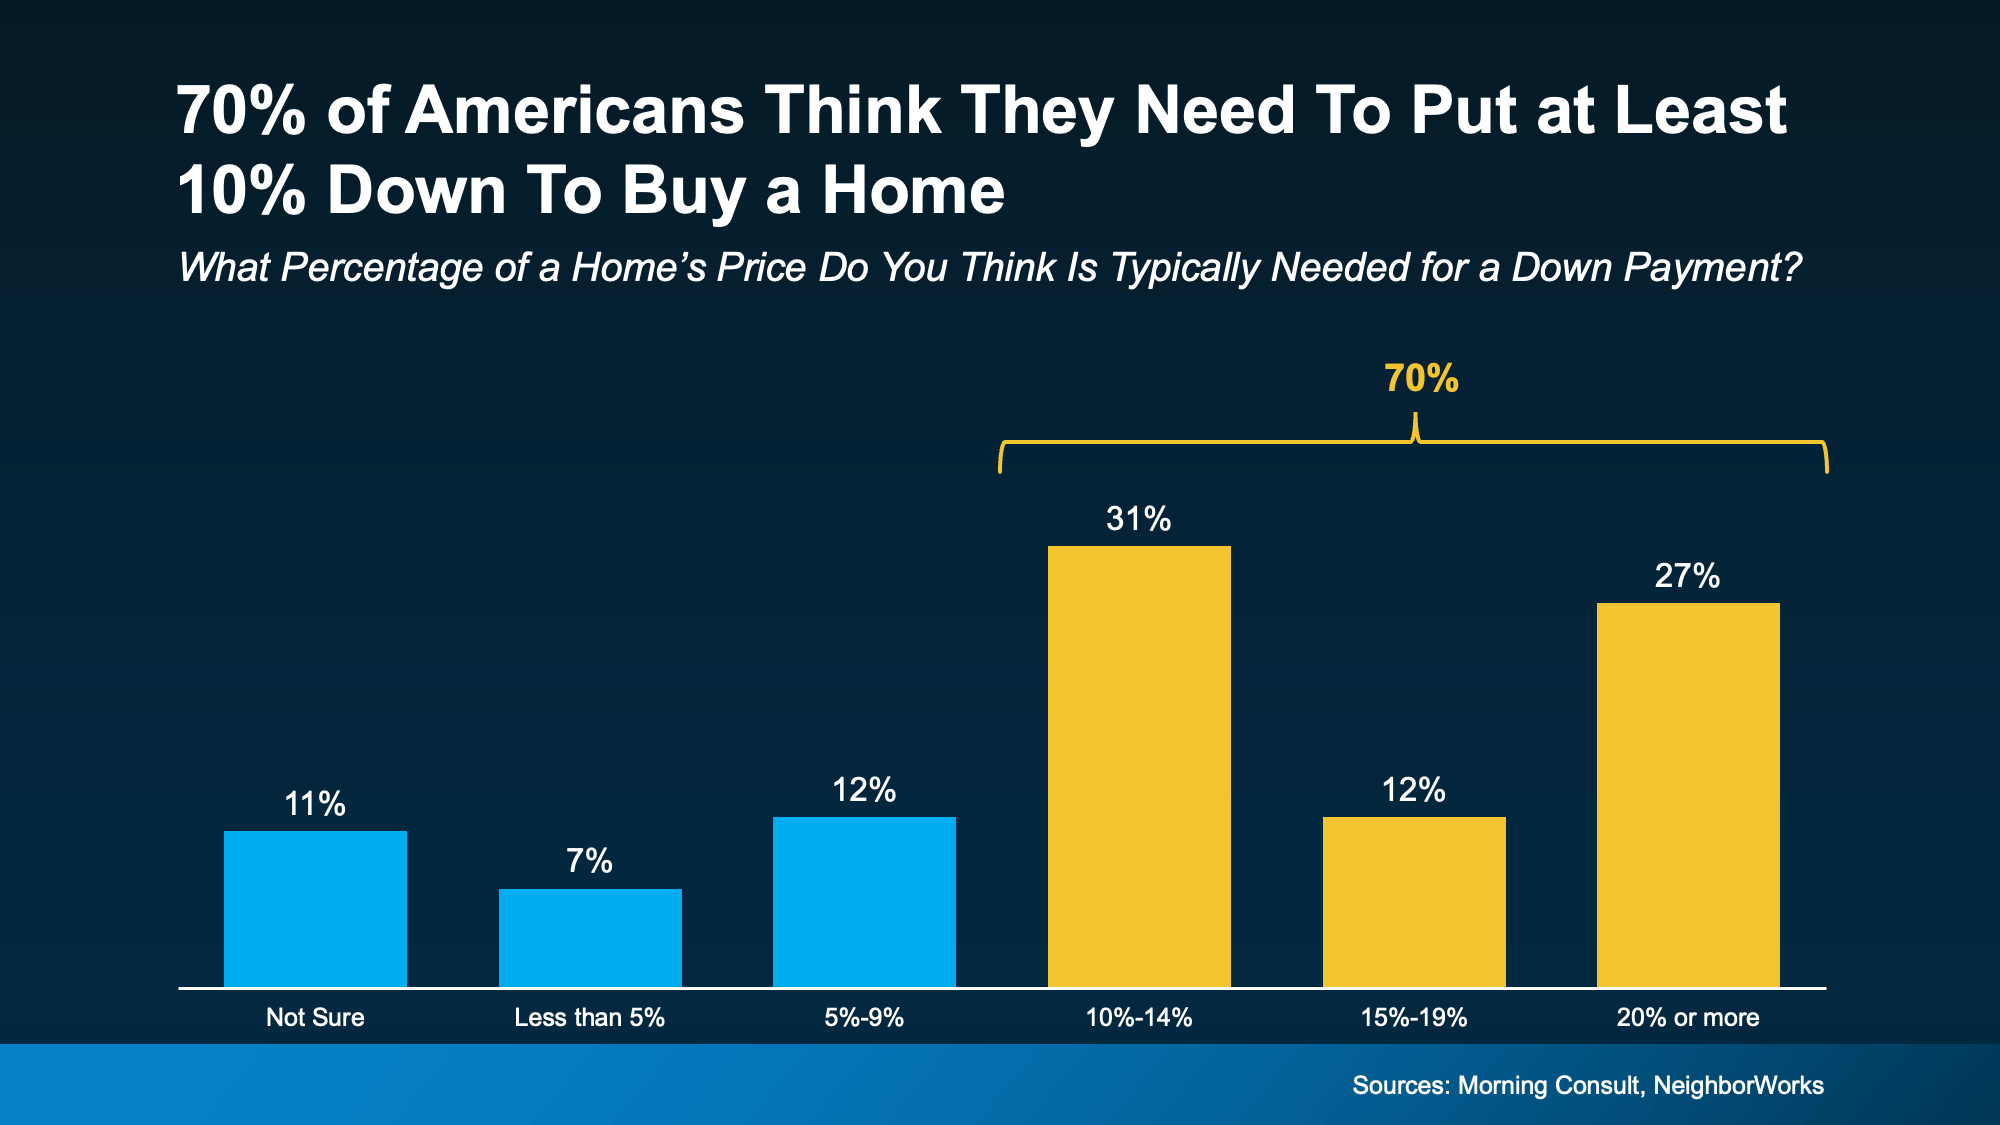
This one stops a lot of people in their tracks. A recent poll from Morning Consult and NeighborWorks shows 70% of Americans think they need to put at least 10% down to buy a home. And 11% aren’t sure what’s required at all (see graph below): 

a graph of a number of blue and yellow squares

The truth? According to the National Association of Realtors (NAR), the typical down payment for first-time buyers has been between 6% and 9% since 2018. But there’s more to the story. If you qualify for an FHA loan, you may only need to put 3.5% down. And VA loans typically don’t require a down payment at all. So, there are options out there that can really make a difference for some buyers.

Myth 2: “It’ll take forever to save up for a down payment.”

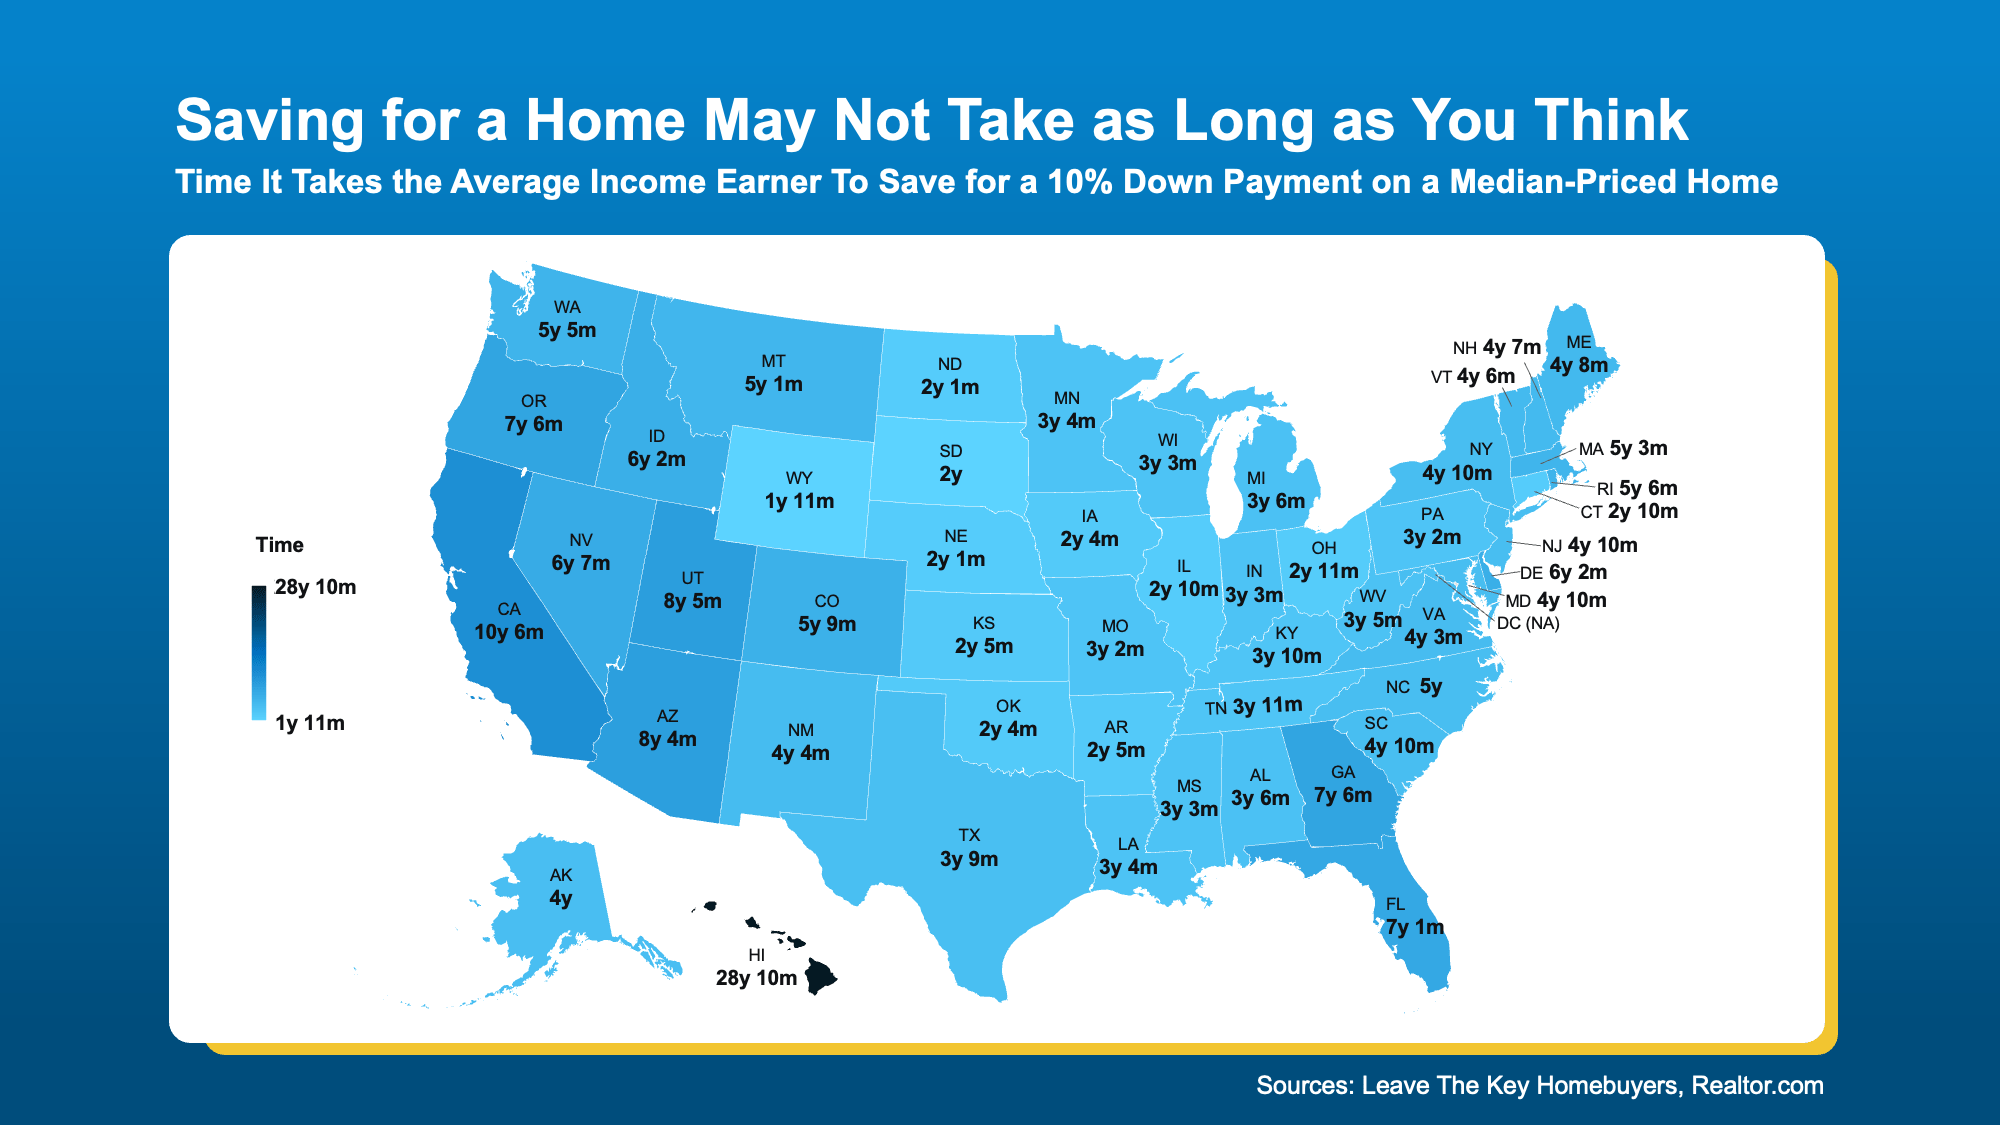
Sure, saving can take time. But it may not have to be as long as you think. In many states, reaching your goal can happen faster than you might expect, especially when you know your budget and have a clear savings plan.

According to a new study, the amount of time varies depending on where you live. The map below shows, on average, how many years it takes to save up for a 10% down payment based on typical home values and income levels in each state (see map below):

But remember, in most cases you won’t even need a down payment as large as 10%. Plus, no matter how much money you end up putting down, it won’t all have to come out of your pocket. Here’s why.

Myth 3: “I have to do it all on my own.”

This is one of the biggest myths of all. The reality is, there are thousands of down payment assistance programs out there, and the same poll from Morning Consult and NeighborWorks shows 39% of people don’t even know about them. That means a lot of potential homebuyers could already be closer to homeownership – they just don’t realize it. 

These assistance programs are designed to help people like you who are ready to own a home but just need a little support getting started. As Miki Adams, President at CBC Mortgage Agency, explains:

“With high interest rates and soaring home prices, down payment assistance is more essential than ever.”

Bottom Line

If you’ve been putting off buying a home because the down payment feels like too much to tackle, let’s talk. You may not need as much as you think, and there are plenty of resources out there, so you don’t have to do it alone. You just need an expert to point you in the right direction.

If a down payment wasn’t holding you back, would you be ready to start your home search?

Posted in Buying
Aug. 1, 2025

Virginia Beach Housing Market Forecasts for the Rest of 2025


If you’ve been watching the market, you’ve likely noticed a few changes already this year. But what’s next? From home prices to mortgage rates, here’s what the latest expert forecasts suggest for the rest of 2025 – and what these shifts could mean for you.

Will Home Prices Fall?

Many buyers are hoping home prices will come down soon. And recent headlines about prices dipping in some areas are making some people believe it's just a matter of time before there’s a bigger drop. But here are the facts.

While home price growth is slowing down, that doesn’t mean we’re headed for a crash. As NAHB explains:

“House price growth slowed . . . partly due to a decline in demand and an increase in supply. Persistent high mortgage rates and increased inventory combined to ease upward pressure on house prices. These factors signaled a cooling market, following rapid gains seen in previous years.”

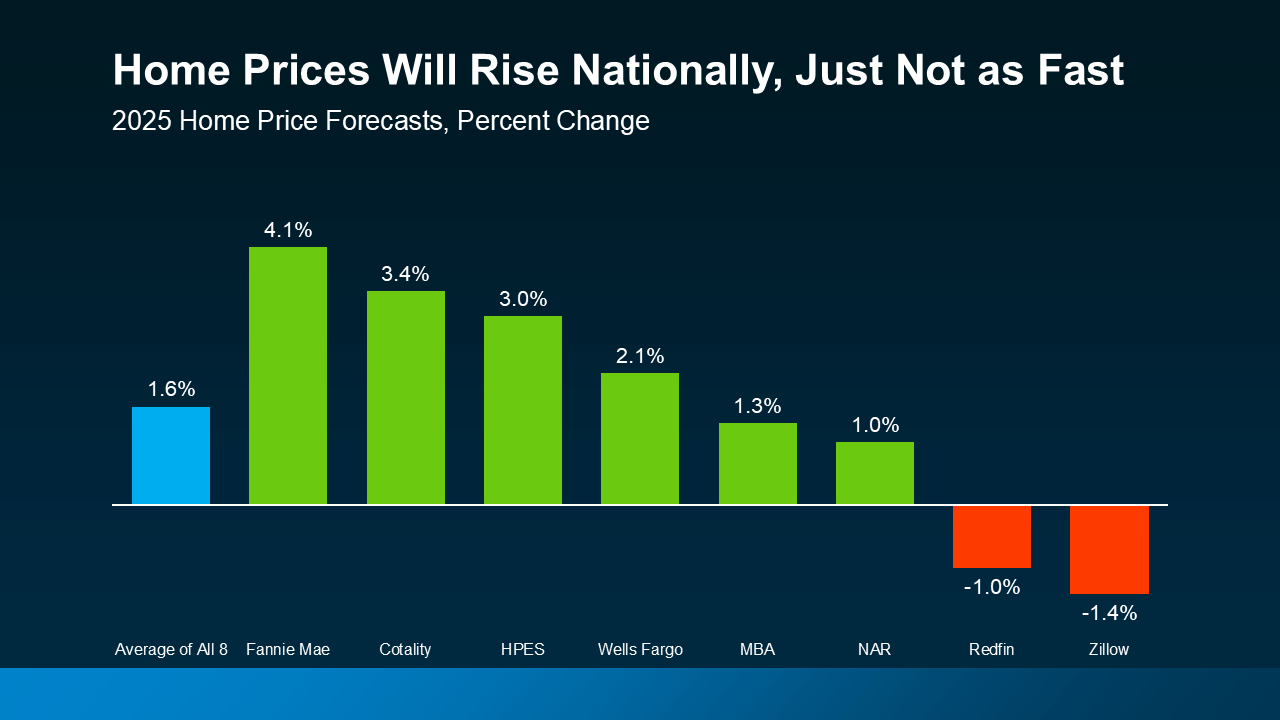
But experts say, even with that slowdown, prices will still rise this year at the national level. The average of 8 leading forecasters shows prices are expected to go up 1.5-2% in 2025 (see graph below):

That means, if you’re waiting for a major drop, experts agree that’s just not in the cards.
Keep in mind, while some markets are already seeing prices come down slightly, the average dip is just -3.5%. That’s a far cry from the nearly 20% decline the market experienced during the 2008 crash.

Plus, those small changes are easily absorbed when you consider how much home prices have climbed over the past few years. Data from the Federal Housing Finance Agency (FHFA) shows prices are up 55% nationally compared to just 5 years ago.

The takeaway? Prices aren’t crashing. They’re expected to keep climbing – just not as quickly these days. And some may argue they’ll be closer to flat by the end of this year. But, again, this is going to vary by market, with some local ups and downs. So, lean on a pro to see the latest price trends for your area.

Will Mortgage Rates Come Down?

Another common thought among today’s buyers is: I’m just going to wait for rates to come down. But is that a smart strategy? According to Yahoo Finance:

"If you’re looking for a substantial interest rate drop in 2025, you’ll likely be left waiting. The latest news from the Federal Reserve and other key economic data point toward steady mortgage rates on par with what we see today."

In other words, don’t try to time the market or wait for a drop that may not be coming. Most experts say rates will remain in the 6s, and current projections have them settling in the mid-6% range by the end of this year (see chart below):

a blue rectangular table with white textAnd that’s not a big change from where they are right now. So, if you need to move, let’s talk about how to make it happen and what you should watch for. Because while rates may not be as low as you want them to be, you don’t want to put your needs on the back burner, hoping for something the data shows isn’t likely to happen.

Working with an expert who is keeping an eye on all the economic factors that can influence mortgage rates is going to be essential this year. That’s because changes in things like inflation and other key drivers could impact how rates move going forward. 

The Takeaway for Buyers and Sellers

Whether you're buying, selling, or thinking about doing both, this market requires strategy, not guesswork. Prices are still rising nationally (just more slowly), and rates are projected to stay pretty much where they are, so the bigger picture is one of moderation – not a meltdown.

Bottom Line

If you want to make a move, your best bet is to focus on your personal situation – not what the headlines say – and work with a real estate pro who knows how to navigate the shifting conditions in our local market.


Let’s talk about what’s happening in our area to build a plan that works for you.

Posted in Buying, Market Updates
July 29, 2025

The U.S. Foreclosure Map You Need To See


Foreclosure headlines are making noise again – and they’re designed to stir up fear to get you to read them. But what the data shows is actually happening in the market tells a very different story than what you might be led to believe. So, before you jump to conclusions, it’s important to look at the full picture.

Yes, foreclosure starts are up 7% in the first six months of the year. But zooming out shows that’s nowhere near crisis levels. Here’s why.

Filings Are Still Far Below Crash Levels

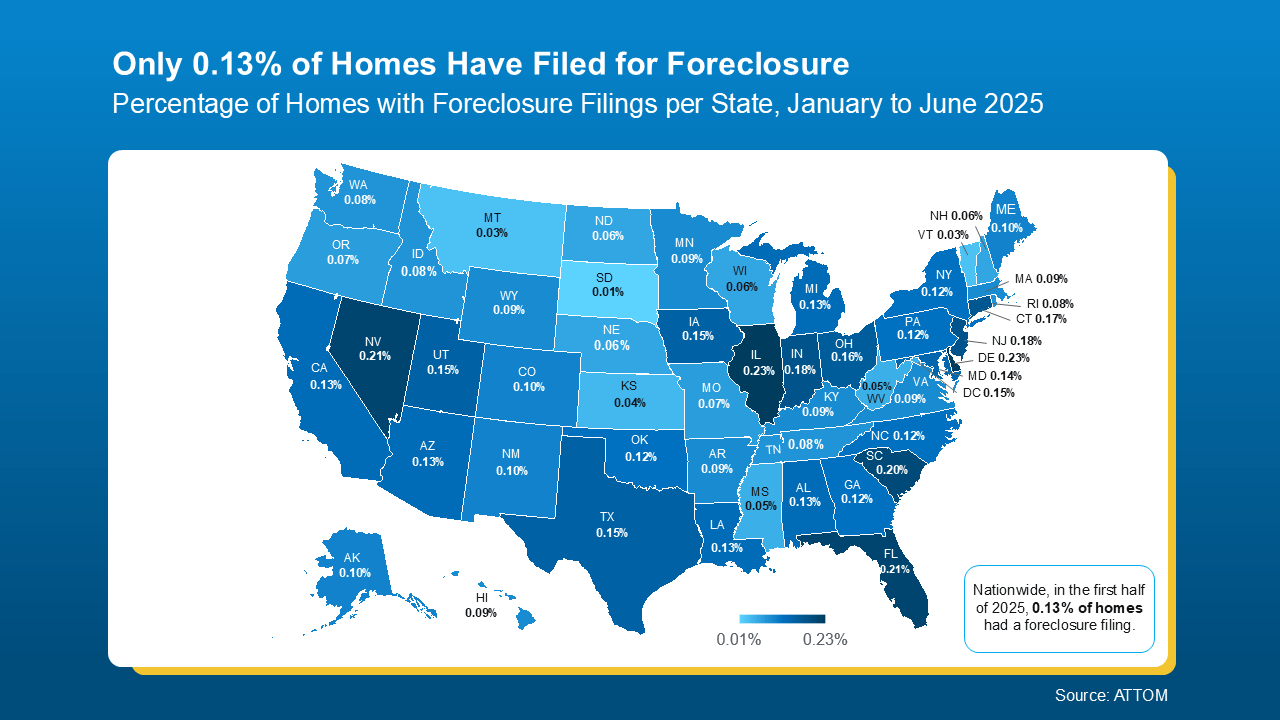
Even with the recent uptick, overall foreclosure filings are still very low. In the first half of 2025, just 0.13% of homes had filed for foreclosure. That’s less than 1% of homes in this country. In fact, it’s even far less than that at under a quarter of a percent. That’s a very small fraction of all the homes out there. But like with anything else in real estate, the numbers vary by market.

Here’s the map you need to see that shows how foreclosure rates are lower than you might think, and how they differ by local area:

a map of the united statesFor context, data from ATTOM shows in the first half of 2025, 1 in every 758 homes nationwide had a foreclosure filing. Thats the 0.13% you can see in the map above. But in 2010, back during the crash? Mortgage News Daily says it was 1 in every 45 homes.

Today’s Numbers Don’t Indicate a Market in Trouble

But here’s what everyone remembers…

Leading up to the crash, risky lending practices left homeowners with payments they eventually couldn’t afford. That led to a situation where many homeowners were underwater on their mortgages. When they couldn’t make their payments, they had no choice but to walk away. Foreclosures surged, and the market ultimately crashed.

Today’s housing market is very different. Lending standards are stronger. Homeowners have near record levels of equity. And when someone hits financial trouble, that equity means many people can sell their home rather than face foreclosure. As Rick Sharga, Founder of CJ Patrick Company, explains:

“. . . a significant factor contributing to today’s comparatively low levels of foreclosure activity is that homeowners—including those in foreclosure—possess an unprecedented amount of home equity.”

No one wants to see a homeowner struggle. But if you’re a homeowner facing hardship, talk to your mortgage provider. You may have more options than you think.

Bottom Line

Recent headlines may not tell the whole story, but the data does. Foreclosure activity remains low by historical standards and is not a sign of another crash.

If you’re simply watching the market and want to understand what’s really going on, or how this impacts the value of your home, let’s connect. I’ll help you separate fact from fear by showing you what the data really says.

Posted in Market Updates
July 25, 2025

The Latest Mortgage Rate Forecasts

If you’re tempted to delay your move in hope that mortgage rates will come down, you may want to rethink that strategy based on the latest forecast. Experts say mortgage rates are projected to stay in the 6s this year. So don’t expect a big drop. If you want to talk about what this means for your move, let's connect. As forecasts change, having an expert who can keep you updated is essential.

Mortgage Rate Forecast

Posted in Market Updates