Hampton Roads Real Estate Blog

Explore real estate advice for Virginia Beach, Norfolk, Chesapeake and the surrounding Hampton Roads communities. Browse articles on buying, selling, neighborhoods and housing market developments from The Morton Group with AtCoastal Realty.

Looking for a location to start your search? Visit our Virginia Beach neighborhood maps or ask us about your next move.

May 17, 2025

Home Projects That ACTUALLY Boost Value


Whether you’re planning to move soon or not, it’s smart to be strategic about which home projects you take on. Your time, energy, and money matter – and not all upgrades offer the payoff you might expect. As U.S. News Real Estate explains:

". . . not every home renovation project will increase the resale value of a home. Before you invest in a swimming pool or new addition, you should consider whether the project will pay itself off by getting prospective buyers in the door when it’s time to sell."

That’s why, before you pick up a power tool or call a contractor, your first step should be talking to a local agent.

Planning Ahead Pays Off

If you plan to move relatively soon, you’ll want to get a jump start on your to-do list. And even if moving isn’t on your radar yet, life can change quickly – and a new job, a growing family, or shifting priorities can fast-track your plans. You don’t want to be scrambling to fix up your home if your timeline changes.

Smart updates now = fewer headaches later.

By planning ahead, you can spread out the work over time, which is easier on your wallet and your stress levels. Plus, you’ll get to enjoy the upgrades while you’re still living there and have the peace of mind your house is ready to impress when it's time to list.

What Buyers Want (and What’s Actually Worth Doing)

If you’re not sure which projects are worth your time and money – here's some information that can help. A study from the National Association of Realtors (NAR) shows which upgrades typically offer the best return on your investment (ROI) (see graph below):
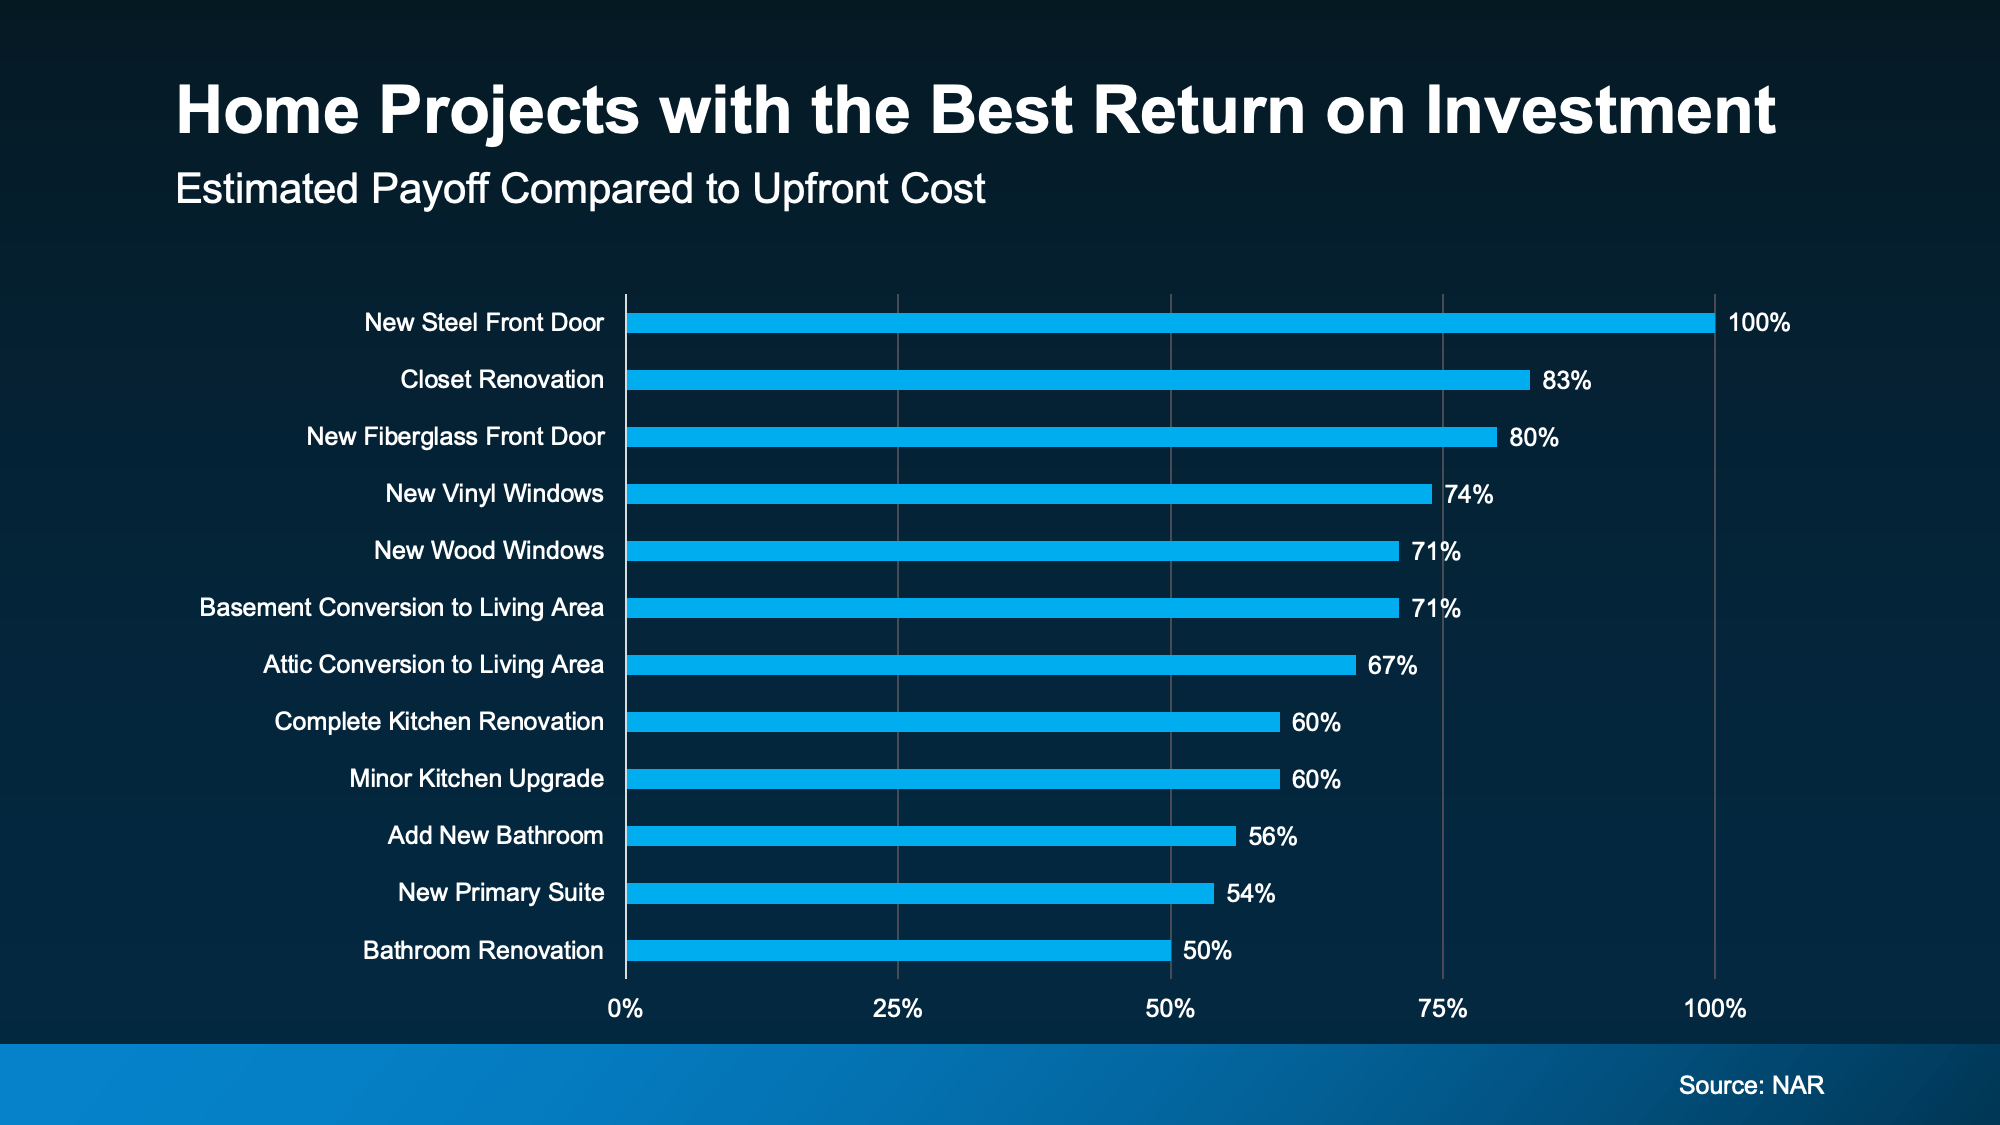
a graph of a costIf an update you're already thinking about overlaps with those high-ROI upgrades, great. Odds are it'll improve your quality of life now and your home’s value later.

But don’t take this list as law. This is based on national data and is the sort of thing that's going to vary based on what’s most sought-after where you live. That’s where your agent comes in. As an article from Ramsey Solutions says:

“The best way to gauge what you can expect in terms of resale value on home improvements—especially if you’re planning to sell soon—is to talk to a real estate agent who is an expert in your market. They’re sure to know the local trends, and they can show you how other homes with the features you want to add are selling. That way, you can make an educated decision before you start ordering lumber and knocking down walls.”

You'll just want to make sure you don't overdo it. Too many high-end updates can make your home the priciest in the neighborhood. That might sound great, but it can actually turn buyers away if it's outside their expected price range for the area. The right agent will help you make smart updates that buyers will love, without going overboard. 

Whether the project is big or small, it pays to be strategic. And an agent is a key piece of that strategy.

Bottom Line

It doesn’t matter whether you plan to move soon or not, it can still pay off to make strategic updates that’ll help you love your home now and stand out later.

What’s one upgrade you’ve been thinking about – and wondering if it’s worth it? Let’s make sure it’ll pay off when the time comes.
Posted in Selling
May 14, 2025

Why Today’s Foreclosure Numbers Aren’t a Warning Sign


When it feels like the cost of just about everything is rising, it’s only natural to wonder what that means for the housing market. Some people are even questioning whether more homeowners will struggle to make their mortgage payments, ultimately leading to a wave of foreclosures. And recent data showing foreclosure filings have increased is only feeding into this fear. But don’t let that scare you.

If you put the latest data into context, it’s clear there’s no reason to think this is a repeat of the last housing crash.

This Isn’t Like 2008

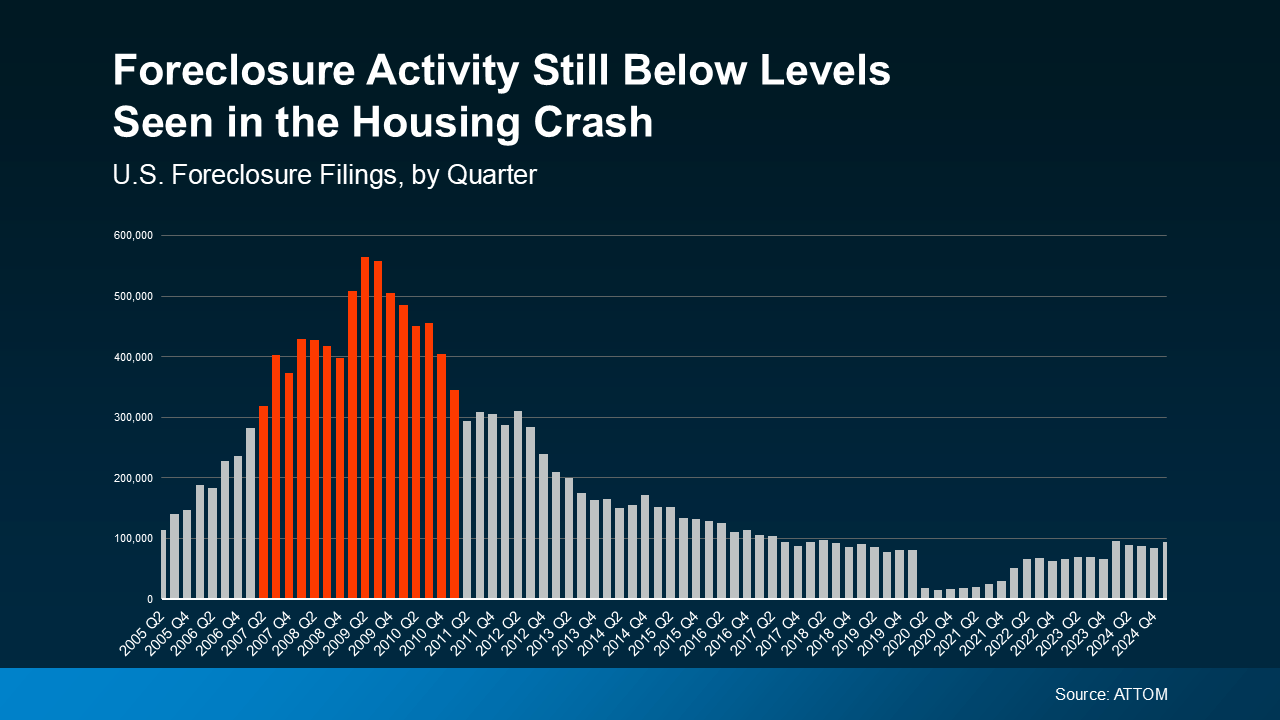
While it’s true that foreclosure filings ticked up in the latest quarterly report from ATTOM, they’re still lower than the norm – and way below levels seen during the crash. And it’s a lot easier to see if you graph that out.

If you compare Q1 2025 (on the right side of the graph) to what happened in the years surrounding the 2008 crash (shown in red), it’s clear the market is in a completely different place (see graph below):

a graph of a graph of a number of falling downBack then, risky lending practices left homeowners with mortgages they couldn’t afford. That led to a wave of foreclosures, which flooded the market with distressed properties, a surplus of inventory, and caused home prices to drop dramatically.

Today, lending standards are much stronger, and most homeowners are in a much better financial position. That’s why filings are so much lower this time.

And just in case you’re looking at 2020 and 2021 and thinking we’ve ramped up since then, here’s what you need to know. During those years, there was a moratorium designed to help millions of homeowners avoid foreclosure in challenging times. That’s why the numbers for just a few years ago were so incredibly low.

So don’t compare today to that low point. If you look at more normal years like 2017-2019, overall foreclosure filings are actually down from what’s typical – and way down from the volume during the crash.

Of course, no one wants to go through the process of foreclosure. And the recent increase is emotional because it’s real lives that are impacted – let's not discount that. It’s just that, as a whole, this isn’t a signal of trouble in the market.

Why We Haven’t Seen a Big Surge in Foreclosures

And here's something else to reassure you: homeowner equity. Over the past few years, home prices have risen significantly. That means today’s homeowners have built up a solid financial cushion. As Rob Barber, CEO at ATTOM, explains:

“While levels remain below historical averages, the quarterly growth suggests that some homeowners may be starting to feel the pressure of ongoing economic challenges. However, strong home equity positions in many markets continue to help buffer against a more significant spike . . .”

Basically, if someone falls on hard times and can’t make their mortgage payments, they may be able to sell their home instead of going into foreclosure. That’s a huge contrast to 2008, when many people owed more than their homes were worth and had no choice but to walk away.

Don’t discount the strong equity footing most homeowners have today. As Rick Sharga Founder and CEO of CJ Patrick Company, explains in a recent Forbes article:

“ . . . a significant factor contributing to today’s comparatively low levels of foreclosure activity is that homeowners—including those in foreclosure—possess an unprecedented amount of home equity.”

Bottom Line

Even with the recent increase, foreclosure numbers are not at the levels seen during the 2008 crash. Plus, most homeowners today are in a much stronger equity position, even with rising costs.

If you are a homeowner who’s facing hardship, talk to your mortgage provider to explore your options.

Posted in Market Updates
May 12, 2025

What You Can Do When Mortgage Rates Are a Moving Target


Have you seen where mortgage rates have been lately? One day they go down a little. The next day, they go back up again. It can feel confusing and even frustrating if you’re trying to decide whether now’s a good time to buy a home.

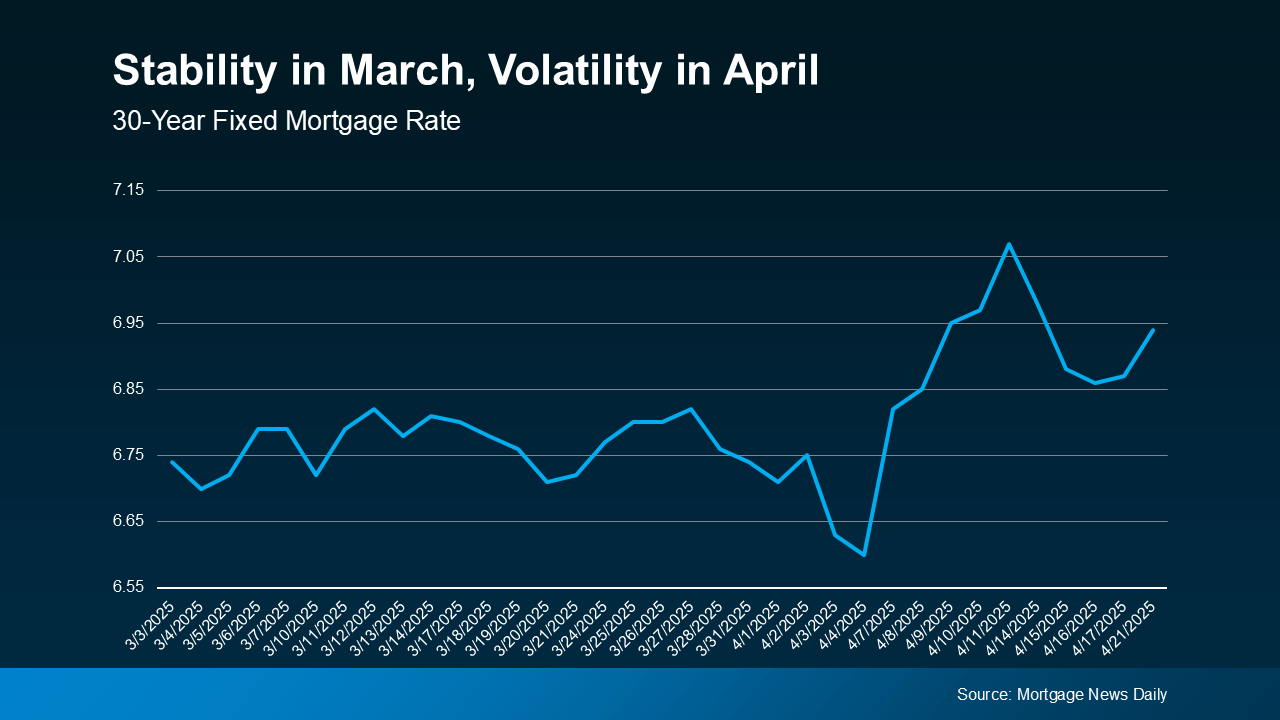
Take a look at the graph below. It uses data from Mortgage News Daily to show that after a relatively stable month of March, mortgage rates have been on a bit of a roller coaster ride in April:

This kind of up-and-down volatility is expected when economic changes are happening.
And that’s one of the reasons why trying to time the market isn’t your best move. You can’t control what happens with mortgage rates. But you’re not powerless. Even with all the economic uncertainty right now, there are things you can do.

You can control your credit score, loan type, and loan term. That way, you can get the best rate possible in today’s market.

Your Credit Score

Your credit score can really affect the mortgage rate you qualify for. Even a small change in your score can make a big difference in your monthly payment. Like Bankrate says:

“Your credit score is one of the most important factors lenders consider when you apply for a mortgage. Not just to qualify for the loan itself, but for the conditions: Typically, the higher your score, the lower the interest rates and better terms you’ll qualify for.”

Keeping your credit score up is key when it comes to qualifying for a home loan. If you’re not sure where your score stands or how to improve it, talk to a loan officer you trust.

Your Loan Type

There are also different types of loans out there, and each one comes with unique requirements for qualified buyers. The Consumer Financial Protection Bureau (CFPB) explains:

“There are several broad categories of mortgage loans, such as conventional, FHA, USDA, and VA loans. Lenders decide which products to offer, and loan types have different eligibility requirements. Rates can be significantly different depending on what loan type you choose. Talking to multiple lenders can help you better understand all of the options available to you.”

Always work with a mortgage professional to figure out which loan makes the most sense for you and your financial situation.

Your Loan Term

Just like there are different loan types, there are also different loan terms. Freddie Mac puts it like this:

“When choosing the right home loan for you, it’s important to consider the loan term, which is the length of time it will take you to repay your loan before you fully own your home. Your loan term will affect your interest rate, monthly payment, and the total amount of interest you will pay over the life of the loan.”

Most lenders typically offer 15, 20, or 30-year conventional loans. Be sure to ask your loan officer what’s best for you.

Bottom Line

You can’t control what’s happening with the economy or mortgage rates, but you can work with a trusted lender and take steps that’ll help you get the best rate possible.

Let’s connect to talk about what you can do today to put yourself in a strong spot for when you’re ready to buy a home.

Posted in Buying, Market Updates
May 7, 2025

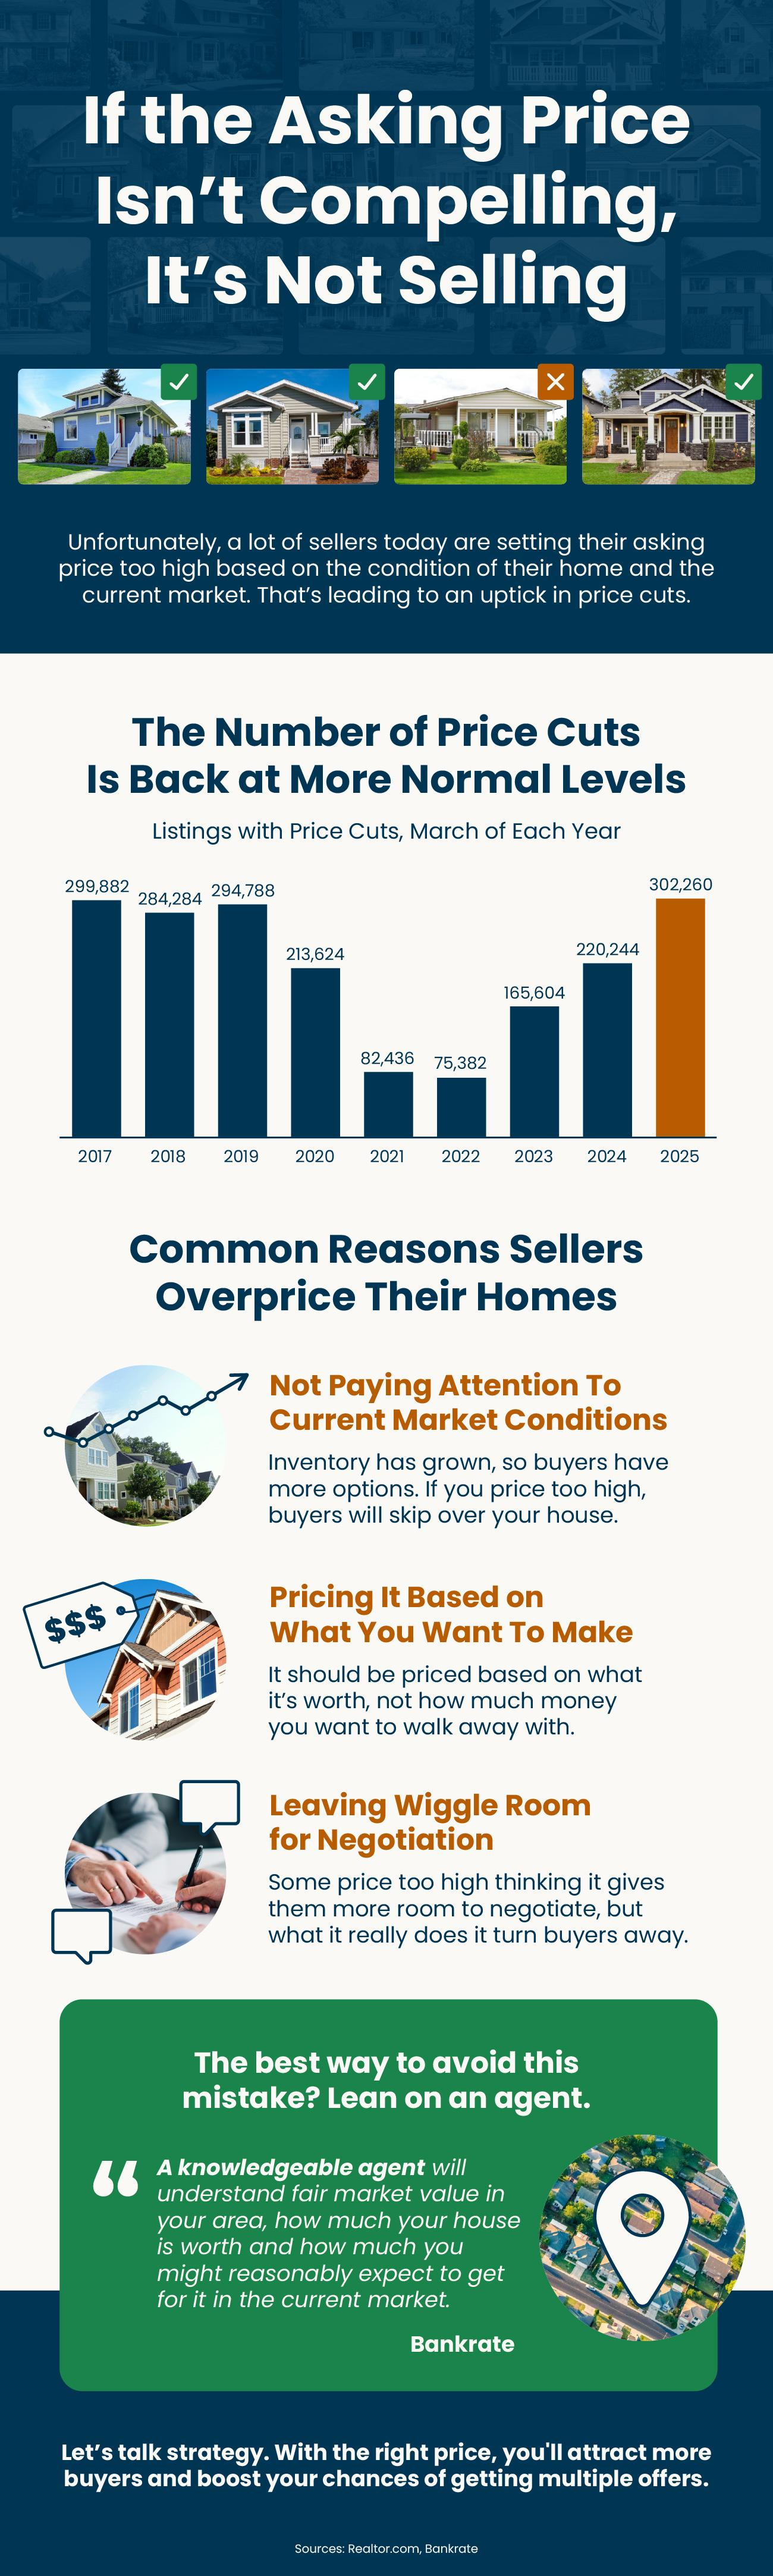
If the Asking Price Isn’t Compelling, It’s Not Selling

If the Asking Price Isn’t Compelling, It’s Not Selling

Posted in Selling
May 1, 2025

Pre-Approval Isn’t Commitment – It’s Clarity


If buying a home is on your radar – even if it’s more of a someday plan than a right now plan – getting pre-approved early is still one of the smartest moves you can make. Why? Because, like anything in life, the right prep work makes things clearer.

The best time to get serious about buying is before you’re ready to buy. Here’s why.

Pre-Approval Helps You Understand Your Numbers

One of the biggest benefits of pre-approval is how it helps you understand your buying power. As part of the pre-approval process, a lender will walk through your finances and tell you what you can borrow based on your income, debts, credit score, and more. That number is power.

Once you have that clarity, you’re no longer guessing. You know what you’re working with. And that gives you the information you need to be able to plan ahead. That way, you’re not falling in love with homes that are outside of your price range – or missing out on ones that aren’t.

Pre-Approval Helps You Move Quickly When You’re Ready

You don’t have to be ready to buy to be ready to buy.

It happens all the time – someone scrolls through listings just for fun, and then BAM – they fall in love with something they see online. But by the time they scramble to connect with an agent and then get pre-approved with a lender, someone else beats them to it, and they lose the home. And you don’t want that to happen to you.

While you can’t control when the right home shows up – you can be ready for it.

Pre-approval isn’t about jumping the gun or rushing your timeline. It’s about making sure you’re ready when it’s go-time. As Experian explains:

“Waiting too long to get a preapproval, however, could leave you at a disadvantage . . . you could find the perfect home, but another buyer could snatch it up while you're waiting for the lender to review your preapproval application. . . getting a preapproval just before you begin actively looking at homes may be your best option.”

Instead of rushing to figure out your numbers, trying to get documentation for your home loan together, and watching the house you love slip away while you wait to hear from your lender, you’re already in the game.

It’s like showing up to the starting line with your shoes tied and your warm-up done – while everyone else is still looking for parking.

But pre-approvals do have an expiration date, so be sure to ask your lender how long it’s good for. Bankrate offers this insight:

“Many mortgage preapprovals are valid for 90 days, though some lenders will only authorize a 30- or 60-day preapproval. If your preapproval expires, getting it renewed can be as simple as your lender rechecking your credit and finances to ensure there have been no major changes to your situation since the first time ‘round.”

The thing is, if you’ve been pre-approved – even if you’re just thinking about casually looking – you have a much better sense of how to navigate your home search within your budget. Plus, you’ll be ready if the perfect home comes along. So why not make it happen?

Bottom Line

Getting pre-approved doesn’t mean you have to buy a house today. But it does mean you’ll know what you’re working with when the right one shows up. If you want to get pre-approved, connect with a lender to get that process started.

In the meantime, let’s have a conversation about what’s on your mind and what you’re looking for.

If the perfect house popped up tomorrow, would you be ready to make a move?

Posted in Buying
April 27, 2025

Are You Saving Up To Buy a Home? Your Tax Refund Can Help


You’ve been working on your savings and dreaming of that moment when you finally have keys to a place that’s truly yours. What you might not realize is that your tax return could give you a little extra cash to help you get there sooner. As Freddie Mac notes:

“ . . . your tax refund from the IRS can be a useful supplement to your homebuying budget.” 

So, if you’re getting a tax refund this year, you can use it to help you pay for some of the upfront costs that come with buying a home, like the down payment and closing costs. And here’s the best part.

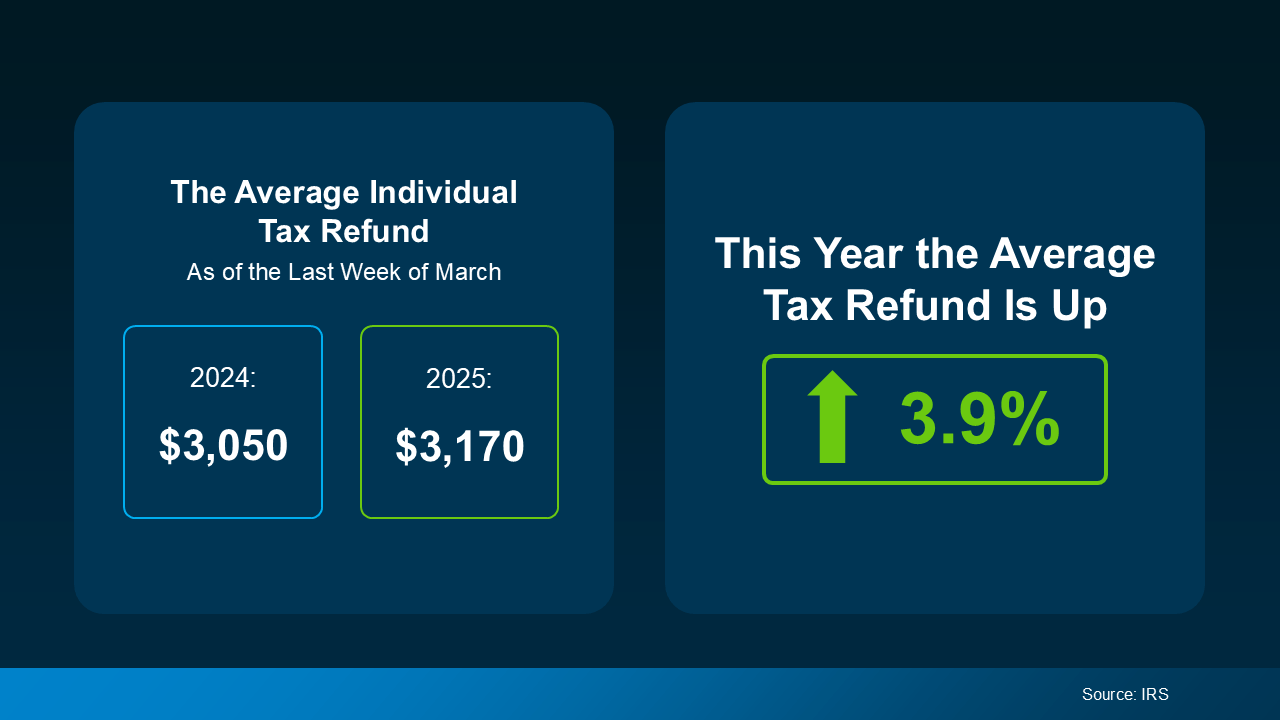
On average, people are getting even more money back in their refunds than they did last year. While it’s not a big increase, the visual below uses data from the Internal Revenue Service (IRS) to show the average individual’s refund is 3.9% higher this year:

a screenshot of a computer

Of course, how much money you may get in your tax refund is going to vary. But when it comes to buying a home, any extra cash can help move things forward. Here are a few examples of how you can put that money to good use, according to Freddie Mac:

  • Save for a down payment – Saving for a down payment can be one of the biggest hurdles for buyers. Setting aside your tax refund for this expense could help you get to your goal faster. Just remember, it’s typically not required to put 20% down.
  • Pay for closing costs – Closing costs include fees for things like the appraisal, title insurance, and underwriting of your loan. They’re generally between 2% and 5% of the total purchase price of the home. So, putting your refund toward these costs can make things more manageable on closing day.
  • Lower your mortgage rate – Your lender might give you the option to buy down your mortgage rate. If you qualify for this option, you could pay up front to have a lower rate on your mortgage. If affordability is tight for you at today’s rates and home prices, this may be worth exploring.

But you don’t have to figure it all out on your own. Working with a team of trusted real estate professionals who understand the homebuying process, what you need to save, and any resources you can tap into will help you make sure you’re ready to buy when the time comes.

Bottom Line

When it comes to saving for a home, every dollar gets you one step closer to your goal. While your tax refund may not be enough to change the game, it can help give your homebuying fund a boost.

What would having your own home mean for you or your family this year? Let’s talk about it and we’ll come up with a strategy for success. 

Posted in Buying
April 22, 2025

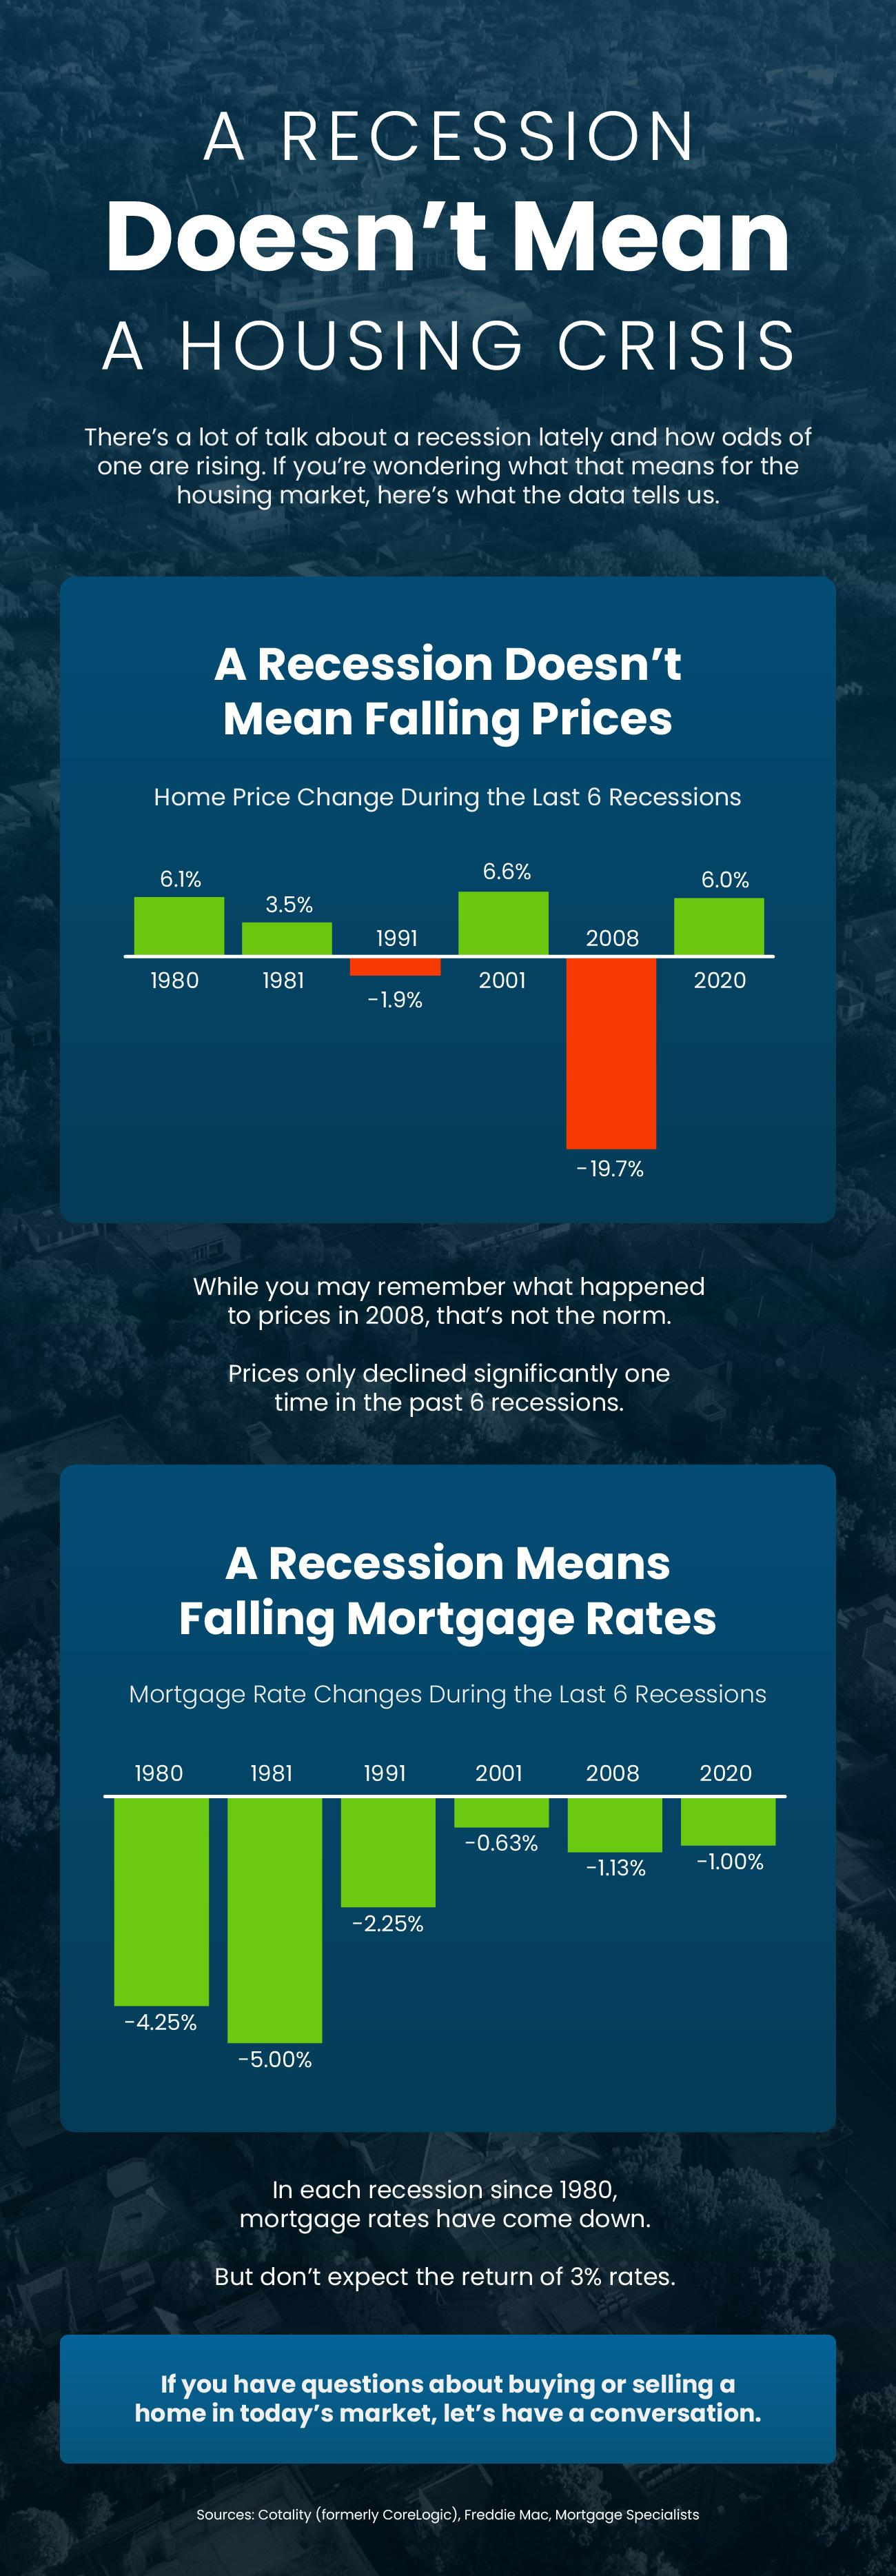
A Recession Doesn’t Mean a Housing Crisis

A Recession Doesn’t Mean a Housing Crisis

Posted in Market Updates
April 16, 2025

4 Ways To Make an Offer That Stands Out This Spring


Now that spring is here, more and more buyers are jumping back into the market, and competition is heating up.

If you’re serious about landing a home you’ll love, you need more than just a wish list. You need a smart strategy – and that starts with working with a great agent who can help you put together a strong offer.

Here are some top tips your agent will share with you that are helping buyers stand out (and win) in today’s market.

1. Don’t Lowball on Price

It’s tempting to start with a super low offer in an attempt to save money. But in a competitive spring market, that could backfire. If the price isn’t reasonable, you could offend the seller and lose out to a better bid. As NerdWallet says:

“If you really want the property, you should avoid offending the seller. So, be wary of placing a so-called lowball offer. One of the most obvious risks of making a lowball offer is outright rejection. . . As a buyer, you’ll need to find a balance between making a fair offer and running the risk of losing the property.”

Your agent can help you understand local pricing trends and what a fair, yet strong offer looks like this season.

2. Consider an Escalation Clause

If you’re worried about competing bids, an escalation clause can help. If you have an escalation clause and the seller gets another offer, it increases yours up to a certain max amount you set. That way you don’t lose out over a small difference. Investopedia explains it like this:

“An escalation clause is a way to automatically escalate your bid by a certain dollar amount, up to a certain ceiling, to compete with other bids.”

Work with your agent to decide if this tactic fits your situation and budget. Just be sure not to stretch beyond what you’re truly comfortable spending and that the home is likely to appraise for the amount you offer.

If the appraisal comes in lower than your offer, you may have to make up the difference out of pocket. Your agent can help you weigh these risks and determine the best approach for your specific situation.

3. Be Intentional About the Concessions You Ask For

While some concessions (like help with closing costs) might be possible, too many demands could make another buyer’s cleaner offer more attractive. As the National Association of Realtors (NAR) notes:

“There are many factors up for discussion in any real estate transaction—from price to repairs to possession date. A real estate professional who’s representing you will look at the transaction from your perspective, helping you negotiate a purchase agreement that meets your needs . . .”

An agent who knows what’s working for other buyers in your area can help you prioritize the most important asks – and avoid ones that could turn off the seller.

4. Consider a Timeline That Appeals to the Seller

Sometimes, it’s not just about price, it’s about timing. Does the seller need extra time to move out? Or do they want to move as soon as possible? Flexibility here can work in your favor. By adjusting your timeline (if you’re able to), you could stand out against other offers. According to Atlas Van Lines:

“Everyone will have a unique timeline depending on the size of the move, the distance they are moving from or to, and personal preferences. It is important to be flexible and adapt the timeline as needed while ensuring you allocate enough time for each step.”

Your agent can communicate with the seller’s agent to find out what matters most, including timing.

Bottom Line

Spring is here – and more buyers are entering the market. Let’s work together to make sure your offer stands out.

What’s one thing you want to feel confident about before making an offer this spring?

Posted in Buying
April 11, 2025

Why You Don't Want To Skip Your Home Inspection


When you finally find the home you want to buy, it’s easy to get caught up in the excitement. You’ve toured the place, imagined your furniture in it, maybe even pictured your morning coffee on the porch. The last thing you want is to slow down the process with more steps or lose out to another buyer’s offer because they skipped their inspection.

But here’s the thing. Buying a home is one of the biggest financial decisions you’ll ever make. And no matter how perfect that house seems, skipping a home inspection is a risk that could cost you a lot more than just time.

What Exactly Is a Home Inspection?

A home inspection gives you a detailed look at the home’s condition, usually after your offer’s accepted but before closing. While what’s covered varies by state, an inspector usually goes over the home’s major systems and structure, including things like the roof, foundation, plumbing, electrical, HVAC, and more.

Why an Inspection Is Worth It

Here’s a quick rundown of some of the biggest benefits of getting an inspection.

  • Helps you avoid unpleasant surprises. A house might seem move-in ready, but could have issues you didn’t see during your walkthrough. Knowing about these before closing day is important. That way, you have a better idea of what work may need to be done to the home.
  • Gives you negotiating power. Depending on what the inspection turns up, you may want to re-negotiate with the seller. For that, lean on your agent. With their help, you can ask the seller to handle repairs before closing day or provide a credit so you can take care of them yourself.
  • Offers you peace of mind. Buying a home is emotional, especially if you’ve been searching for a while. An inspection helps take some of the uncertainty off your plate, so you can move forward with confidence.

A few hundred dollars upfront for the home inspection could save you thousands in surprise repairs later. As the National Association of Realtors (NAR) says:

“Failure to obtain a home inspection could potentially cost you a great deal of money and hassles in the long run.”  

Why You Don’t Want To Waive Your Inspection

According to the latest data from NAR, nearly 1 in 4 buyers are waiving (or removing) the inspection contingency when they buy a home. And with spring being peak homebuying season and buyer activity already heating up, you may be thinking about doing that yourself. As Realtor.com points out:

“ . . . if you're in a hot real estate market where homes are getting multiple offers, there might be a temptation to skip an inspection when you really want the house. However, waiving a home inspection comes with sizable risks.”

But skipping the inspection is a gamble that doesn’t necessarily pay off. Just remember, there are other ways to make your offer attractive to sellers, like being flexible with the closing date. Before making an offer, talk to your agent about other ways to get a seller’s attention without sacrificing your peace of mind.

Bottom Line

Even if skipping an inspection sounds like a way to make your offer more competitive or speed things up, it’s risky. It’s not just extra time and documentation, it’s a smart step that protects your wallet, your investment, and your future.

If you could ask a home inspector one question before buying, what would it be? Let me know and I’ll make sure it’s the first thing we bring up.

Posted in Buying
April 7, 2025

Does Your Current Virginia Beach Home Fit Your Retirement Plans?


Retirement isn’t just a milestone. It's the beginning of something really special. After years of hard work, it’s finally time to slow down, explore new passions, and live life on your own terms.

But with this exciting chapter comes some big choices. And one of the biggest is this: does your current home still make sense for the lifestyle (and budget) you want in this next phase of life?

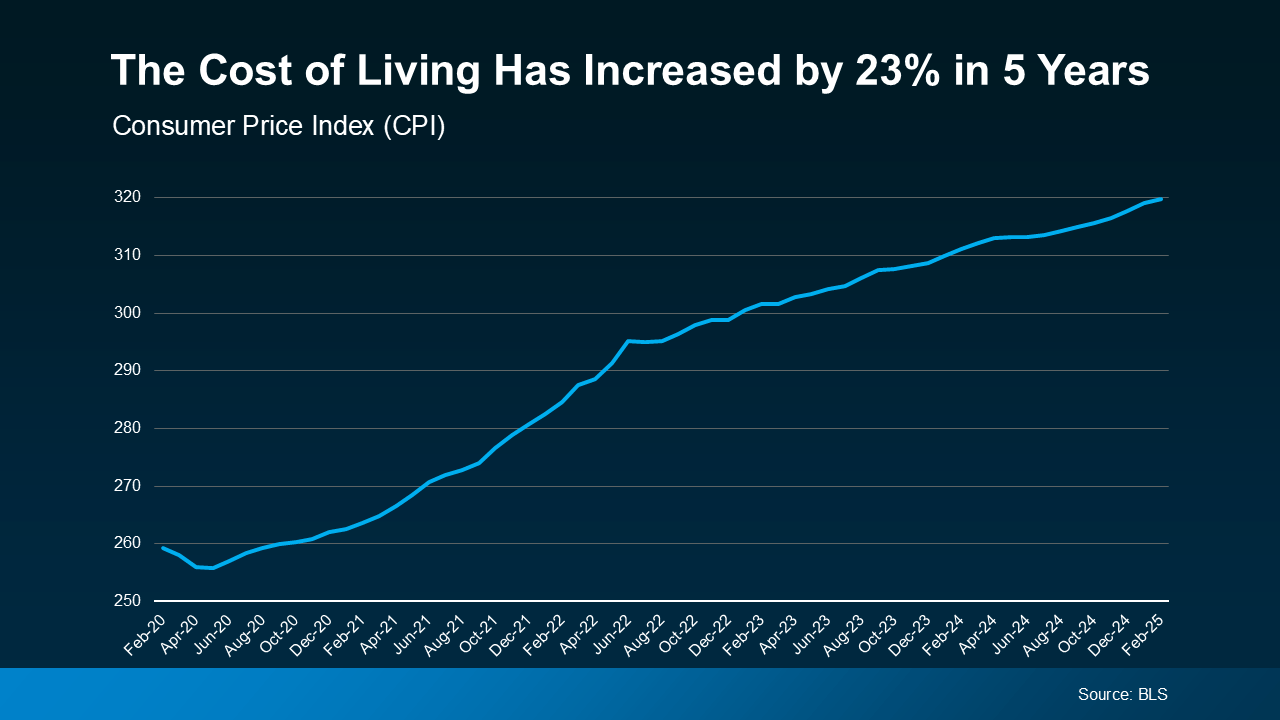
That’s an especially important question right now. Just in the past five years, the cost of living has jumped by 23% according to the Bureau of Labor Statistics (BLS). That’s based on the Consumer Price Index (CPI), which is how changes are tracked in the average price consumers pay for goods and services (see graph below):

a graph with a line going upWhen you’re thinking about how to make your retirement savings last, those rising expenses matter. And if you’ve started to wonder whether your money will stretch as far as you need it to go, don’t worry. You may have more control than you think.

One way many retirees are protecting their savings is by relocating. Because your dollars do go further in some places.

Moving to an area with a lower cost of living can help you save on regular expenses like your housing, utilities, and taxes – especially if you downsize at the same time.

And that can free up room in your budget for the things that make retirement some of the best years of your life: travel, hobbies, spoiling your grandkids, or any of the other things you’ve been dreaming about doing in this next phase.

That’s not to say you have to move. It just means you’ll want to think about where you plan to live and make sure you’ve got enough savings to cover actually living there. It's all about planning. As Go Banking Rates explains:

“How much you should have saved for retirement depends on a few key factors, including your location. Where you choose to spend your golden years is critical.”

And you don’t always have to go far. Sometimes it’s out of state, but other times moving to the suburbs instead of living near the city can make a big difference. And that’s worth thinking about as you plan for your next chapter.

Whether you’re considering downsizing, moving closer to your grandkids, or heading to an area where you can stretch your savings, a real estate agent can help. They’ll work with you to explore the options that make sense for your goals – and can help make selling your current house easier. They can also connect you with trusted agents in other parts of the country if you're considering a big move.

Bottom Line

You’ve worked hard to build a future you can enjoy. If your current home or location no longer supports that, it may be time to explore what’s next.

What does your ideal retirement look like? And could a move help make it even better? Let’s talk about how to make that vision a reality.

Posted in Selling